translate English
 پارسی
English
Englishپارسی
English
Englishپارسی EnglishپارسیEnglishپارسی
U.S. total vehicle sales rose to an annualized 16.00M units in December (15.70M expected, 15.60M prior), surprising to the upside and pointing to firmer auto demand as 2025 ended. The beat suggests consumers were still willing to spend on big-ticket items, potentially helped by improved supply availability and incentives—an important signal given the sensitivity of autos to financing costs.
Market impact: Mildly supportive for USD and U.S. cyclicals at the margin—stronger sales lean against recession narratives, though it can also keep markets alert to demand-driven inflation stickiness. Treasuries may see a modest headwind if the data adds to “growth resilience” pricing.
The Atlanta Fed’s GDPNow estimate for Q4 eased to 2.7% (3.0% expected, 3.0% prior), implying slightly softer real-time growth tracking versus the previous update. A move of this size typically reflects incremental data inputs—often from consumption, trade, or inventory components—rather than a regime change, but it does reinforce a “cooling, not collapsing” growth narrative.
Market impact: Mildly supportive for Treasuries and slightly USD-negative at the margin—lower growth tracking can reduce pressure for higher yields, though the bigger driver remains how inflation prints evolve. Equities may take it as neutral-to-positive if it supports a soft-landing path without triggering recession fears.
U.S. Treasury bill auction yields edged down, signaling steady demand for front-end paper. The 3-month bill stopped at 3.540% (prior 3.570%), while the 6-month bill cleared at 3.475% (prior 3.500%). The modest decline suggests slightly softer near-term rate expectations and/or improved liquidity demand, consistent with markets leaning marginally toward an easier policy path versus prior pricing.
Market impact: Mildly supportive for Treasuries and slightly USD-negative at the margin—lower front-end yields can cap dollar carry support. Impact is usually limited unless the move is echoed across the curve or reinforced by dovish Fed messaging and softer macro data.
The U.S. dollar was pressured on Monday after Minneapolis Fed President Neel Kashkari told CNBC he sees a risk the unemployment rate could “pop” higher, a dovish signal for a 2026 FOMC voter. Rate-cut expectations edged up modestly: Fed funds futures still imply an 82.8% probability the Fed holds at the Jan. 27–28 meeting, down slightly from 83.4% on Friday (CME FedWatch), suggesting markets are inching toward a higher sensitivity to labor-market cooling.
Market impact: Mildly USD-negative and Treasury-supportive at the margin; risk assets can benefit if more officials echo a labor-slowdown narrative, but follow-through depends on incoming jobs and inflation data.
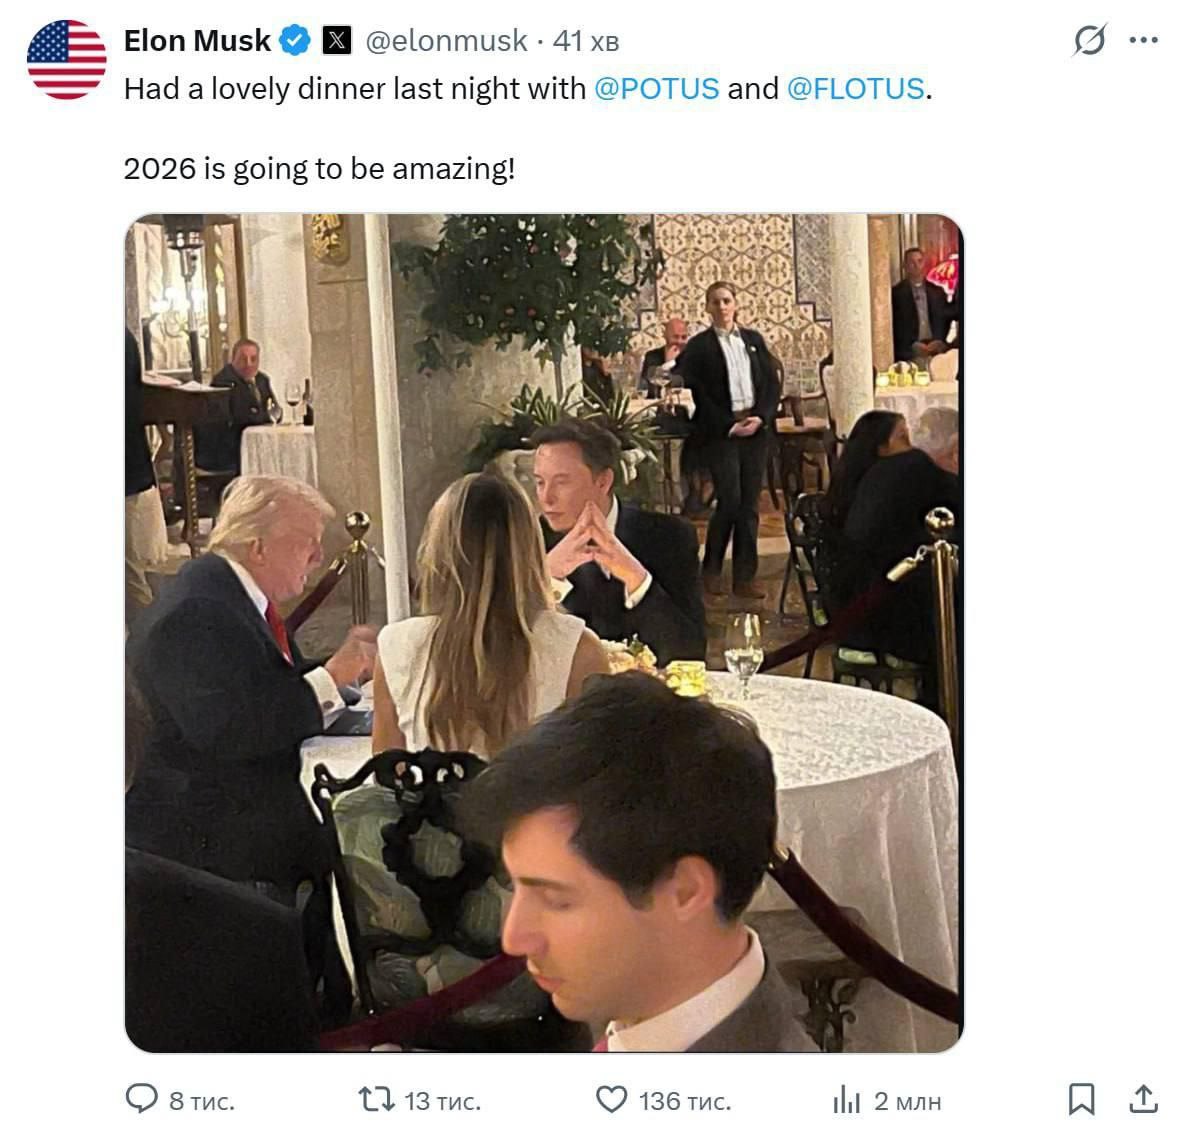
Elon Musk shared a photo from a dinner with President Donald Trump and First Lady Melania Trump, calling the evening “lovely” and saying, “2026 is going to be amazing.” The post reinforces signs of a détente after a high-profile 2025 split, with the two also appearing publicly together at Charlie Kirk’s memorial service on September 21, 2025—a notable reset point in the relationship narrative.
Market impact: Likely limited for broad markets, but potentially supportive for “political-access premium” in Musk-linked equities and suppliers (regulatory/tender optics). Any sustained follow-through would matter more if it translates into concrete policy signals on tech regulation, government contracts, or industrial strategy.
U.S. Secretary of State Marco Rubio said Washington’s Venezuela campaign is “not over,” telling NBC that the U.S. will continue to seize sanctioned oil tankers and reserve the right to strike vessels suspected of transporting drugs toward the United States, keeping maritime pressure in place until U.S. conditions are met. The message reinforces that near-term market transmission is likely to run through energy flows, shipping risk, and sanctions enforcement, rather than a rapid change in Venezuela’s on-the-ground production capacity.
Market impact: Modestly supportive for near-term crude risk premia and energy volatility; negative for LatAm risk sentiment at the margin, with spillover potential into shipping costs and safe-haven demand if enforcement escalates.
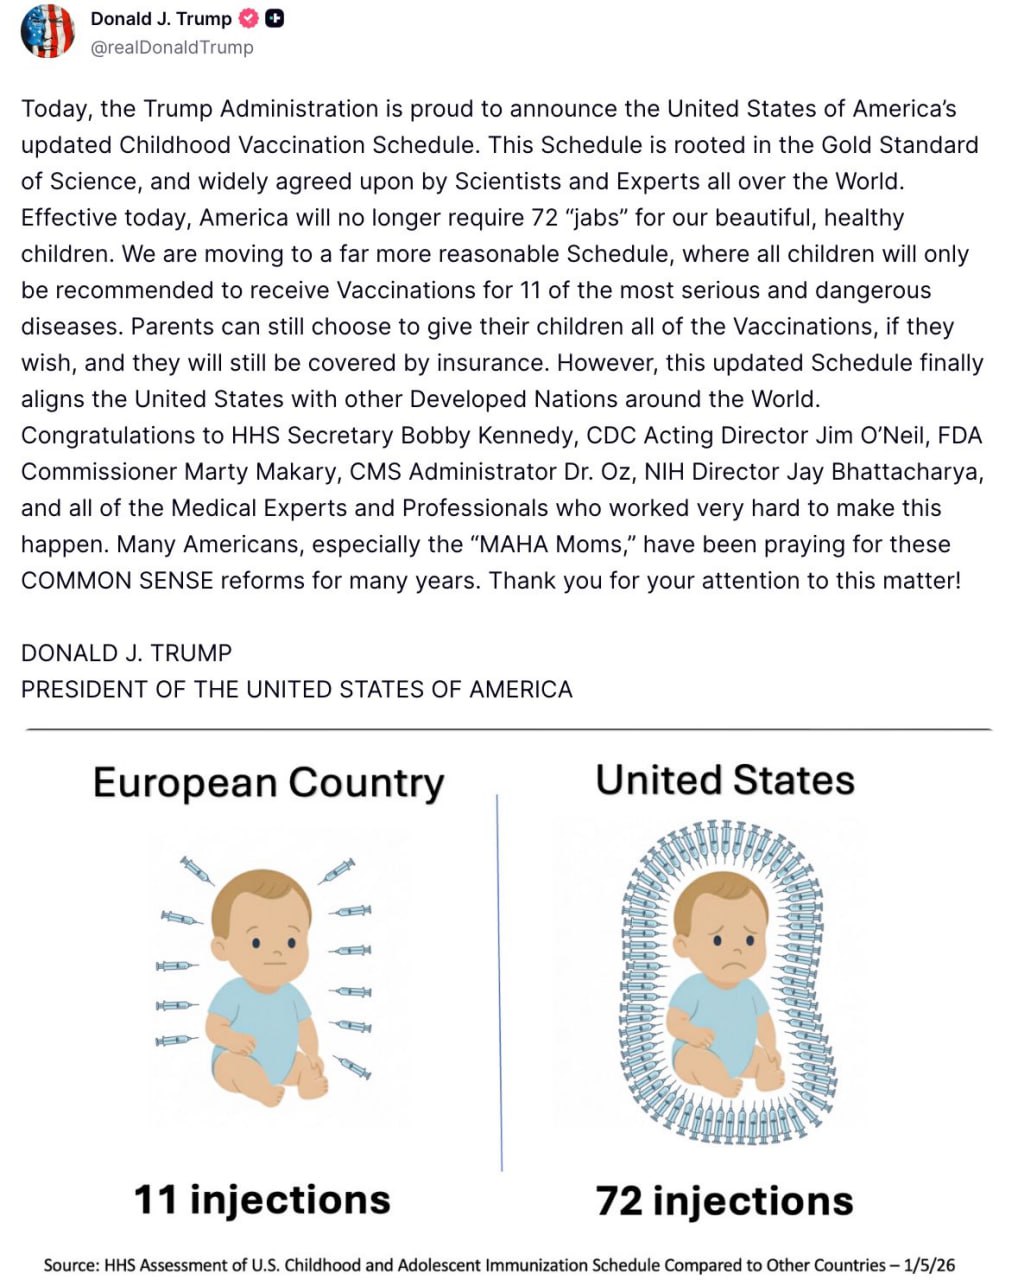
The Trump administration has ordered a major overhaul of the U.S. childhood immunization schedule, reducing universally recommended childhood vaccines from 17 to 11 and shifting several vaccines (including flu, rotavirus, hepatitis A/B, RSV, and some meningitis strains) to high-risk-only or shared clinical decision-making categories. Trump framed the move as “common sense” and said babies would no longer get “72 jabs”—a figure often used to describe the total number of vaccine doses through age 18 under prior recommendations (including annual shots such as flu, and in some counts COVID), though the number of actual injections can be lower due to combination/oral vaccines. Physician groups and public-health experts have sharply criticized the change and warned it could increase preventable disease risk, while noting the process bypassed standard advisory review.
Market impact: Potentially negative for vaccine manufacturers and related healthcare supply chains on U.S. demand expectations, while raising policy and litigation headline risk across healthcare. Broader macro impact is likely limited unless changes materially affect outbreaks, hospital capacity, or state-level coverage rules.
U.S. ISM data showed manufacturing remained under pressure in December, with the headline ISM PMI at 47.9 (48.3 expected, 48.2 prior), keeping the sector in contraction. New orders edged up to 47.7 (prior 47.4), indicating demand softened less than before but is still not back to growth. The employment index improved to 44.9 (prior 44.0), yet remains deep in contraction, consistent with ongoing factory labor caution. Prices paid held high at 58.5 (59.0 expected, 58.5 prior), underscoring sticky input-cost pressures even as activity stays weak—an unfavorable mix of soft growth and firm price components.
Market impact: Mildly supportive for Treasuries and slightly USD-negative at the margin—softer-than-expected PMI reinforces cooling activity, but elevated prices complicate the “easy cuts” narrative and can keep the front end sensitive. For equities, the message is mixed: weaker growth signals weigh on cyclicals, while sticky prices may limit relief rallies in rate-sensitive segments.
The Federal Reserve’s balance sheet rose to $6,641B (prior $6,557B), signaling a modest expansion in aggregate assets. In contrast, reserve balances held by depository institutions fell to $2.853T (prior $2.934T), indicating a drawdown in system reserves even as the headline balance sheet increased. The combination can reflect shifting liability composition (e.g., changes in the Treasury General Account or usage of the overnight reverse repo facility) and suggests liquidity conditions remain in flux rather than on a straight-line tightening or easing path.
Market impact: Typically modest on its own, but the direction is slightly supportive for Treasuries if markets interpret lower reserves as tighter marginal liquidity. For USD, impact is usually limited unless the move coincides with broader funding stress signals; risk assets may stay more sensitive to front-end rate expectations than to these weekly balance-sheet shifts.
The U.S. S&P Global Manufacturing PMI came in at 51.8 in December (51.8 expected, 52.2 prior), matching consensus while easing from the prior month. The index remains above 50, indicating manufacturing is still expanding, but the slight step-down suggests growth momentum cooled into year-end. The steady-but-softer reading is consistent with a manufacturing sector that is stabilizing rather than accelerating, keeping the broader growth narrative dependent on services and labor-market resilience.
Market impact: Largely neutral for USD—an in-line print reduces surprise risk, while the small deceleration can keep Treasury yields supported at the margin if it aligns with other cooling activity indicators. For risk assets, the above-50 level is mildly supportive, but not strong enough on its own to materially shift rate-cut/rate-hold pricing without confirmation from jobs and inflation data.
U.S. initial jobless claims fell to 199K, well below 219K expected and down from 215K previously, pointing to continued strength in near-term labor conditions. Continuing claims also declined to 1,866K from 1,913K, suggesting fewer workers are staying on unemployment rolls. The 4-week average ticked up to 218.75K (from 217.00K), but remains consistent with a tight labor market.
Market impact: Mildly supportive for USD and front-end yields—softer layoff dynamics can reduce the urgency for rapid easing, though markets will still focus on inflation and broader employment reports for confirmation.
U.S. regional data sent a mixed-but-slightly-better signal in December. Chicago PMI rose to 43.5 (vs 39.8 expected, 36.3 prior), improving materially but still below 50—indicating manufacturing remains in contraction. In Texas, services showed modest stabilization: Dallas Fed Services Revenues ticked up to 0.1 from -2.5, while the Texas Services Sector Outlook stayed negative at -3.3 (prior -2.3), implying sentiment remains cautious even as activity metrics firm.
Market impact: Mildly supportive for risk sentiment at the margin—better-than-expected Chicago PMI can ease recession fears, but sub-50 readings keep Treasuries supported and cap USD upside unless broader national indicators confirm a turn.