translate English
 پارسی
English
Englishپارسی
English
Englishپارسی EnglishپارسیEnglishپارسی
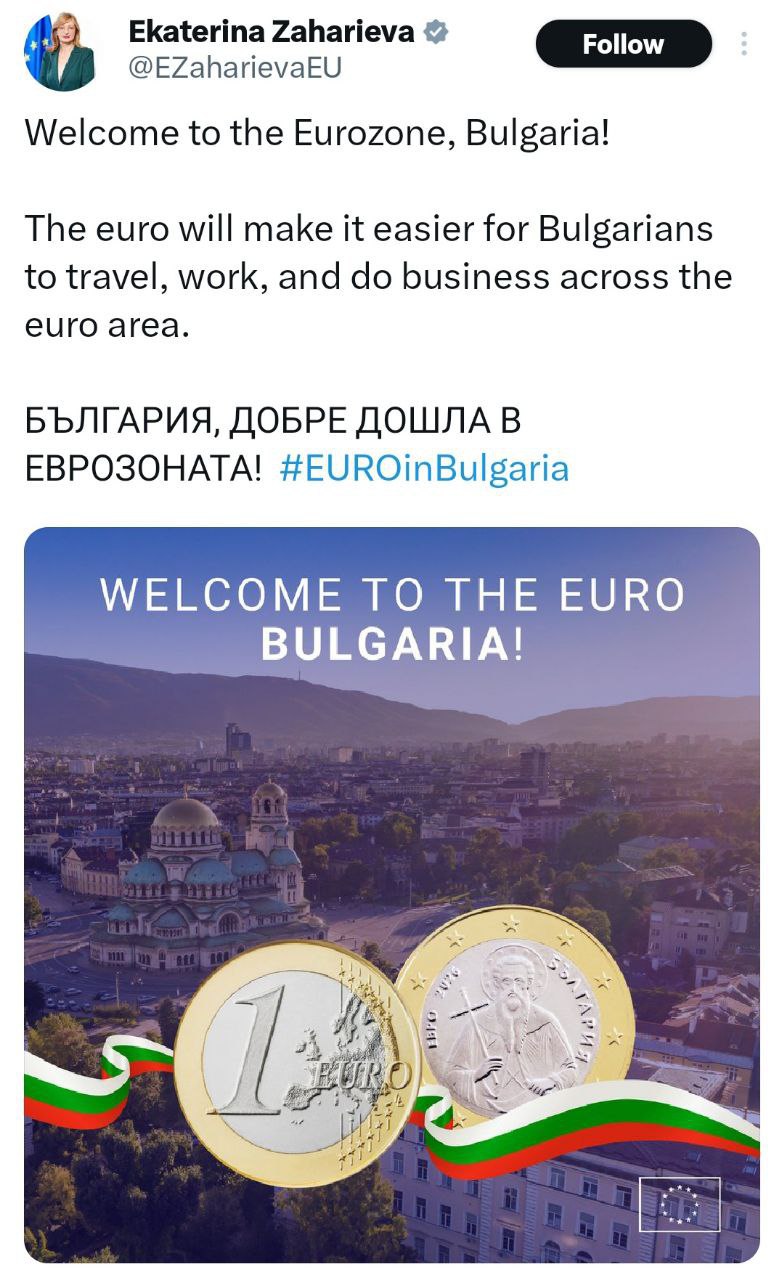
Bulgaria officially entered the euro area on January 1, 2026, replacing the Bulgarian lev with the euro and becoming the 21st member of the currency union. The changeover follows EU/ECB approvals, with the long-standing fixed conversion rate set at 1 EUR = 1.95583 BGN, and a short dual-circulation period in which the lev remains temporarily usable for cash payments while change is given in euros. While policymakers frame the switch as deeper EU integration and improved institutional influence (including Bulgaria’s seat on the ECB Governing Council), parts of the public remain concerned about potential price increases and broader economic strain—especially given domestic political volatility.
Market impact: Typically, supportive for Bulgaria’s macro risk profile over time—removing residual currency-conversion friction and further anchoring policy credibility—but near-term sentiment can be sensitive to perceived “euro-related” price hikes and political noise. Spillover to EUR is likely limited; the cleaner channel is Bulgaria asset pricing (local banks, sovereign spreads) and confidence effects.
Spain’s car registrations rose 9.4% m/m in December (prior -2.7%), indicating a monthly rebound in new vehicle demand. However, registrations fell -2.2% y/y (prior 12.9%), swinging into contraction on an annual basis and suggesting underlying demand momentum softened versus a strong comparison period. The mixed signal points to short-term improvement in activity but a more cautious consumer backdrop heading into early 2026, with affordability and financing costs still key constraints.
Market impact: Limited direct impact on EUR, but mildly negative for Spain-linked consumer cyclicals at the margin—y/y weakness can reinforce the broader “soft demand” narrative in the euro area. If confirmed by retail and confidence data, it could add to expectations of a more accommodative ECB stance later in 2026.
Eurozone lending indicators strengthened in November, pointing to a gradual easing in credit headwinds. Loans to non-financial corporations rose 3.1% y/y (prior 2.9%), while private sector loan growth held slightly firmer at 2.9% y/y (2.8% expected, 2.8% prior). The pickup in corporate lending suggests financing conditions may be loosening at the margin after a prolonged tightening cycle, though the pace remains consistent with a slow, controlled recovery rather than a broad-based credit boom.
Market impact: Mildly supportive for EUR and euro-area risk sentiment—improving credit flow can underpin growth expectations and help offset weak manufacturing signals. However, it is unlikely to shift ECB pricing materially on its own; markets will still anchor on inflation, wages, and hard activity data to gauge the timing and scale of any policy pivot.
The HCOB Eurozone Manufacturing PMI slipped to 48.8 in December (49.2 expected, 49.6 prior), undershooting forecasts and signaling a renewed loss of momentum in the region’s industrial sector. Remaining firmly below the 50 threshold indicates manufacturing stayed in contraction into year-end, reinforcing the view that the euro area’s growth mix remains heavily reliant on services while factories continue to face weak demand and persistent margin pressure.
Market impact: Mildly negative for EUR and supportive for core bonds—softer manufacturing momentum strengthens the “low growth” narrative and can keep markets biased toward easier ECB policy later in 2026. European cyclicals may remain capped unless incoming orders and output indicators show clearer signs of bottoming.
Eurozone broad money (M3) rose to €17,189.3B in November (prior €17,085.8B), while annual M3 growth accelerated to 3.0% y/y (2.7% expected, 2.8% prior). The upside surprise suggests liquidity conditions are gradually improving and that the post-tightening monetary drag is easing at the margin—though money growth at these levels still points to a slow, controlled normalization rather than an aggressive credit upswing.
Market impact: Mildly supportive for EUR and euro-area risk sentiment—firmer money growth can be read as a small tailwind for activity expectations. However, the move is unlikely to materially shift ECB pricing on its own; markets will still focus primarily on inflation, wages, and hard-activity indicators to time any policy pivot.
Switzerland’s official reserve assets rose to CHF 852.4B in November from CHF 844.9B previously, indicating a pickup in reserve accumulation. The increase may reflect valuation effects and/or foreign-exchange operations as authorities manage currency conditions amid a strong franc backdrop.
Market impact: Neutral-to-mildly supportive for CHF—higher reserves suggest active management, but near-term FX direction remains driven by global risk sentiment and SNB policy guidance.
Spain’s core CPI held at 2.6% y/y in December, while headline CPI rose 0.3% m/m and 2.9% y/y (slightly above the 2.8% estimate, but below 3.0% prior). The EU-harmonised measure was steady at 3.0% y/y, with HICP up 0.3% m/m, pointing to persistent but not re-accelerating price pressure. On activity, retail sales jumped 6.0% y/y in November (prior 3.9%), signaling firmer household demand, while the current account surplus widened to €7.18B in October (prior €1.87B), improving the external position.
Market impact: Mildly supportive for EUR—stronger Spanish demand and a larger external surplus help the growth/flow backdrop, while steady core inflation keeps the ECB’s disinflation comfort from improving materially at the margin.
Switzerland’s KOF Leading Indicator rose to 103.4 in December, beating expectations (101.5) and improving from 101.7 previously. The upside surprise suggests a better near-term growth signal and improving forward-looking sentiment, indicating Switzerland’s activity outlook is stabilizing or strengthening at the margin.
Market impact: Mildly supportive for CHF and Swiss cyclicals—stronger growth signals can reduce dovish pressure, though CHF direction still hinges heavily on broader risk sentiment and SNB policy guidance.
France’s total number of jobseekers fell to 3,129.3K in November from 3,150.8K previously (down about 21.5K), pointing to a modest improvement in labor-market conditions. While one month does not set a trend, a sustained decline would be consistent with tighter labor supply and could keep wage/inflation monitoring in focus.
Market impact: Mildly supportive for EUR and modestly hawkish for front-end rates on the margin, but typically a low-volatility release unless reinforced by broader euro-area labor and inflation data.
Italy’s non-EU trade balance rose to a surplus of €6.92B in November (prior €5.32B), indicating a stronger external position versus the previous month. The wider surplus suggests net trade with non-EU partners became more supportive, either via firmer exports, softer imports, or both, helping offset broader growth headwinds.
Market impact: Slightly supportive for EUR at the margin—an improving trade surplus strengthens the external backdrop, though FX impact is typically limited unless echoed across the wider euro area.
Switzerland’s ZEW expectations index declined to 6.2 in December (prior 12.2), indicating a notable deterioration in forward-looking sentiment. While the reading remains slightly positive, the drop suggests optimism is fading and the outlook is becoming more cautious amid a softer growth backdrop and persistent external uncertainties.
Market impact: Slightly supportive for CHF on a risk-off tilt, but dovish-leaning for rates—cooler expectations can reinforce a cautious SNB stance; FX reaction will depend on broader global risk sentiment and yield differentials.
Spain’s producer prices fell -2.5% y/y in November (prior 0.8%), a notable swing into negative territory that signals a rapid cooling in upstream price pressures. The move suggests disinflation is reasserting itself at the producer level, which can filter through to consumer prices with a lag if sustained.
Market impact: Dovish for EUR rates—softer producer inflation supports expectations for easier ECB policy and keeps euro-area inflation risks skewed to the downside; FX impact is usually limited unless broader CPI expectations reprice.