 English
 پارسی


Watch the analytical Video
United States
Last week reinforced the market’s base case of a “moderating but resilient” U.S. economy—an environment that can justify a higher-for-longer Fed stance and keeps the timing of rate cuts heavily dependent on the next few inflation and labor-market prints. The week ahead is holiday-shortened and earnings-heavy, with rates and Fed-related headlines likely to remain the primary swing factors for both the dollar and U.S. equity multiples.
U.S. Economy Review — Second Week of 2026
Cooling inflation, firm activity, tight labor, and a housing market that responds quickly to rates—while builders remain cautious.
The second week of 2026 delivered a broadly constructive macro message. Growth momentum stayed firm, core inflation continued to ease, and labor-market conditions remained tight. In aggregate, the economy appears to be cooling in prices without materially rolling over in activity, a combination that typically keeps the Federal Reserve biased toward patience rather than rapid easing.
Growth and Real Activity: Momentum Remains Firm
High-frequency growth tracking stayed elevated. The Atlanta Fed’s GDPNow estimate for Q4 held strong at 5.3% (vs 5.1% expected/prior), reinforcing the view that the economy entered 2026 with meaningful carryover momentum.
Hard activity data also leaned upbeat:
- Industrial Production (Dec): +0.4% m/m (vs +0.1% expected; +0.4% prior)
- Manufacturing Production (Dec): +0.2% m/m (vs -0.2% expected; +0.3% prior)
- Capacity Utilization: 76.3% (vs 76.0% expected; 76.1% prior)
Regional manufacturing surveys supported a better tone:
- Philly Fed (Jan): 12.6 (vs -1.6 expected; -8.8 prior)
- NY Empire State (Jan): 7.70 (vs 0.80 expected; -3.70 prior)
Within the Philly Fed details, demand improved (New Orders 14.4 vs 5.7), while capex intentions stayed firm (CAPEX 30.3 vs 29.1). Pricing pressure remained elevated but cooled modestly (Prices Paid 46.9 vs 49.3), and the employment component moderated (9.7 vs 13.0). Overall, the growth picture points to resilience rather than rollover.
Inflation: Core Is Well-Behaved, but Pipeline Signals Are Mixed
Consumer inflation prints were encouraging, particularly for core:
- CPI (Dec): 0.3% m/m; 2.7% y/y (in line)
- Core CPI (Dec): 0.2% m/m (below 0.3% expected); 2.6% y/y (below 2.7% expected)
This keeps the disinflation narrative intact and suggests inflation can continue to cool even with activity holding up.
However, upstream/tradables indicators were firmer:
- Import Prices (Nov): +0.4% m/m (vs -0.1% expected; 0.0% prior)
- Export Prices (Nov): +0.5% m/m (vs 0.2% expected; 0.0% prior)
That divergence matters. Core CPI looks favorable now, but persistent import-price strength—via FX, freight, or commodities—can reintroduce pipeline pressure. The takeaway is constructive: inflation is improving, but the “plumbing” warrants monitoring.
Labor Market: Layoffs Stay Contained
Weekly labor data continued to signal tight conditions and limited layoffs:
- Initial Jobless Claims: 198K (vs 215K expected; 207K prior)
- Continuing Claims: 1,884K (vs 1,890K expected; 1,903K prior)
- 4-week average: 205K (vs 211.5K prior)
This profile is consistent with employers remaining reluctant to cut aggressively—supportive for income stability and consumption, even if hiring cools at the margin.
Consumers and Housing: Activity Responds to Rates, Sentiment Lags
Consumption: mixed, but not weak.
- Real Earnings (Dec): -0.3% m/m, highlighting that inflation-adjusted wage momentum can be uneven even as inflation moderates.
- Redbook (YoY): 5.7%, pointing to still-positive high-frequency retail activity (with typical volatility).
- November retail sales were stronger than expected (+0.6% m/m, ex-autos +0.5%, control group +0.4%), suggesting underlying demand remained firm even if some cooling emerged later.
Housing: transactions stabilize; builders remain cautious.
- Existing Home Sales (Dec): 4.35M (vs 4.21M expected; 4.14M prior), +5.1% m/m
- New Home Sales (Oct): 737K (vs 716K expected; 711K prior), -0.1% m/m
- NAHB Housing Market Index (Jan): 37 (vs 40 expected; 39 prior)
Mortgage conditions improved modestly:
- MBA 30-year rate: 6.18% (vs 6.25%)
- MBA applications: +28.5% w/w, with rebounds in both purchase and refinance activity
The message is clear: housing remains highly rate-sensitive—activity responds quickly when financing conditions ease. Builder sentiment, however, still reflects skepticism about durability, consistent with persistent affordability constraints and uneven inventory dynamics.
Financial Conditions and Flows: Foreign Demand for U.S. Assets Stands Out
Cross-border flows were a notable positive surprise:
- TIC Net Long-Term Transactions (Nov): +$220.2B (vs $48.7B expected; $30.9B prior)
- Overall Net Capital Flow (Nov): +$212.0B (vs -$22.5B prior)
- Foreign buying of U.S. Treasuries (Nov): +$85.6B (vs -$60.1B prior)
Short-term funding rates firmed modestly:
- 4-week bill: 3.595% (vs 3.550% prior)
- 8-week bill: 3.600% (vs 3.540% prior)
Liquidity indicators were stable to slightly easier:
- Fed balance sheet: $6,582B (vs $6,574B prior)
- Reserve balances: $3.062T (vs $3.023T prior)
Strong inflows alongside stable liquidity help explain why risk assets can remain supported even as the market continues to debate the timing and pace of Fed easing.
Fed Implications and Near-Term Outlook
The week’s combination of firm activity (GDPNow, industrial production), very low claims, and contained core inflation supports a Fed strategy of waiting for clearer evidence rather than rushing to ease. In short: growth is holding up, and inflation—particularly core—continues to behave.
U.S. Week Ahead: Earnings Take the Wheel as the S&P 500 Tests 7,000
The coming week is holiday-shortened and earnings-heavy, with rates—and any Fed-related headlines—likely to remain the dominant drivers of both the USD and U.S. equity multiples. The S&P 500 closed January 16 at 6,940, leaving it within reach of 7,000 psychological and technical thresholds. For a sustained break higher, markets will likely need two conditions: (1) constructive guidance from bellwether earnings and (2) contained yields. A rejection near 7,000, particularly if accompanied by firmer yields, would raise the risk of a swift de-risking move—especially as post–options-expiration dynamics can widen ranges and accelerate sector rotation.
On the macro and policy front, investors continue to balance resilient activity—which keeps the “higher-for-longer” rate risk in play—against Fed leadership/independence noise that can rapidly reprice yields and the dollar. The baseline USD setup remains modestly supported as long as yields stay firm and policy uncertainty sustains a safe haven bid. Meaningful USD downside would more likely require a cleaner risk-on impulse paired with a decisive decline in yields.
Key Events and Market Catalysts
Event risk begins with U.S. markets closed Monday (Jan 19) for MLK Day, which typically means thinner liquidity and elevated positioning risk into Tuesday. Tuesday (Jan 20) also serves as a “catch-up” session for delayed Fed statistical releases.
Wednesday (Jan 21, 8:30 a.m.) brings Housing Starts and Building Permits (Dec)—a high-signal read on the housing cycle and other rate-sensitive sectors (with some scheduling uncertainty flagged). This is followed by Pending Home Sales (Dec) at 10:00 a.m. Construction Spending is also due Wednesday; recent trends suggest improvement led by home-improvement activity, even as single-family and parts of nonresidential remain pressured. Our base case is flat construction spending in October (0.0%) after +0.3% in September.
Thursday (Jan 22) is the week’s macro fulcrum, featuring the Q3 2025 “third” GDP estimate, Corporate Profits, and GDP by Industry, alongside Initial Jobless Claims—a cluster that can quickly reprice rates and the dollar. The same day also brings Personal Income and Spending, where the consumer picture remains bifurcated (higher earners resilient, lower earners softer). Expected tax relief (OBBBA cuts) may provide incremental support. Building on November retail sales (+0.6% m/m) and a +0.4% control group, we look for personal outlays of +0.5% and personal income +0.3% in November. Inflation, however, is likely to remain sticky early in 2026, with PCE improving more slowly than CPI. We estimate headline and core PCE at 2.8% y/y in both October and November, before more durable disinflation resumes later in 2026 as tariff effects fade.
Friday (Jan 23) brings the S&P Global Flash Manufacturing PMI (Jan) the first major activity read for January. Throughout the week, markets will also take their cue from major earnings and guidance, notably Netflix, Johnson & Johnson, and Intel, alongside any Fed-independence or legal headlines that could jolt yields, the USD, and overall risk appetite.
DXY Technical Analysis | Daily
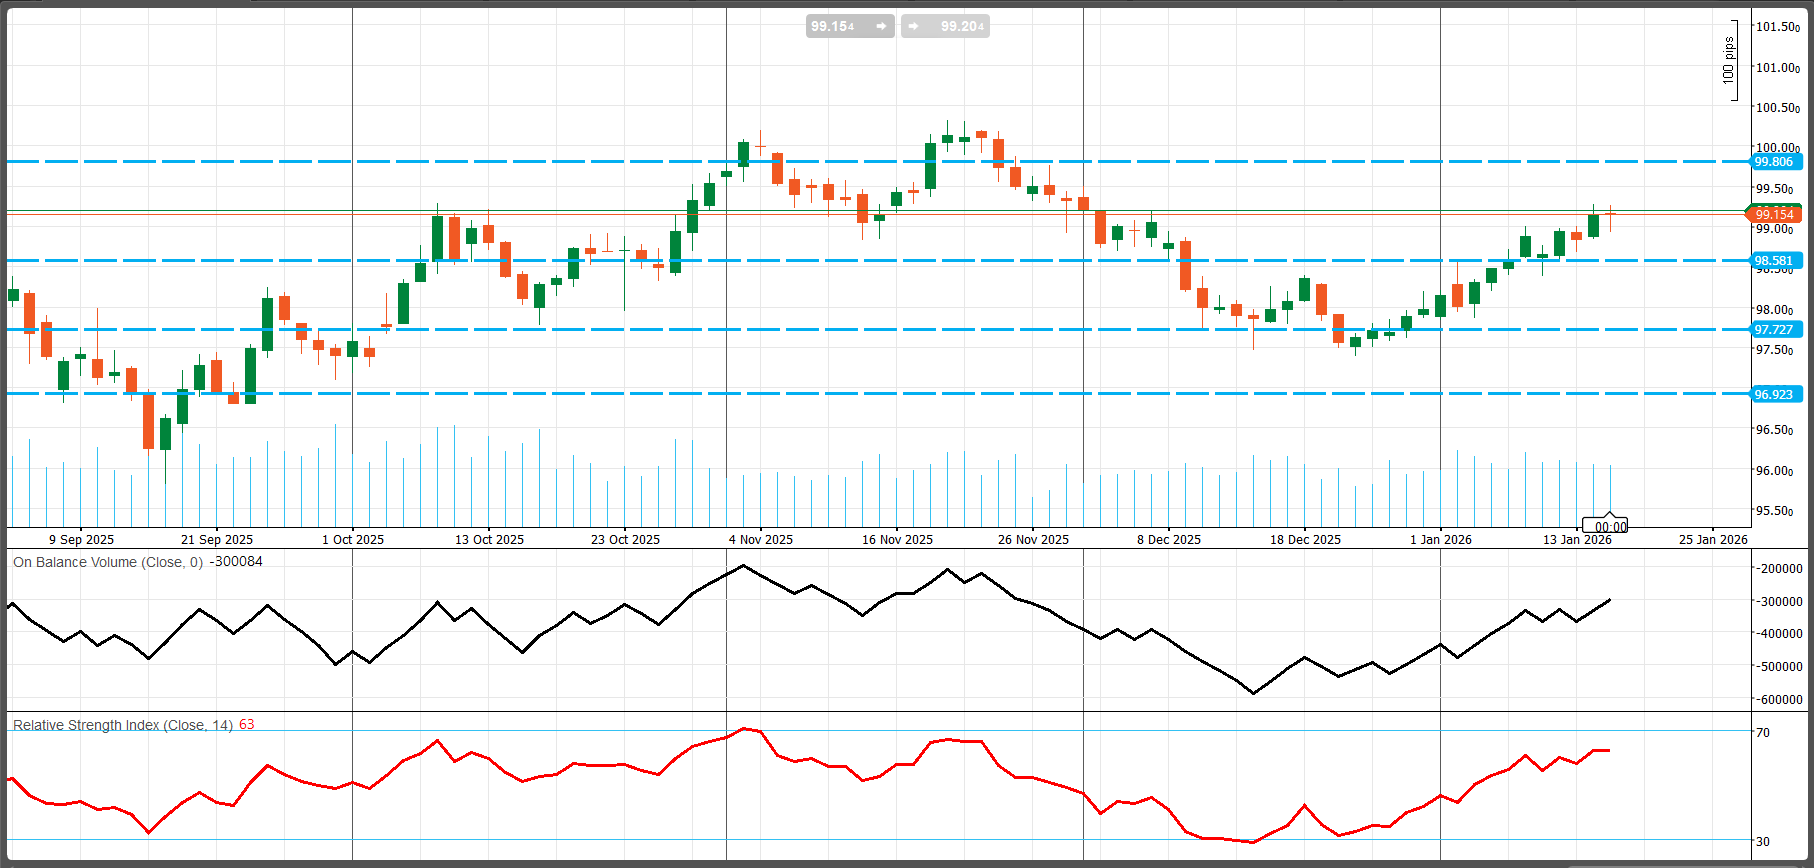
Since the late-December low, DXY has built a clean short-term recovery structure, printing higher lows and higher highs as it rebounded from the ~97.7 area into the 99.1–99.2 region. Zooming out, however, the broader tape still reads as range-bound rather than trend—DXY has largely oscillated between 96.9 and 100.0 from September through January, and price is now back in the upper half of that range.
Importantly, DXY is now pressing into a defined supply zone. It has reclaimed 98.53 and pushed toward ~99.15, but the real decision point sits at 99.80–100.00. Until that band breaks on a convincing daily close, the advance should be treated as a recovery within a broader range, not a fully re-established uptrend.
Momentum and Confirmation (RSI + OBV)
- RSI (14) ~63: constructive bullish momentum, but not overbought (still below 70). This typically supports continuation if price can clear resistance.
- OBV rising off the December trough: a constructive confirmation signal, suggesting the January move has improving participation—more consistent with accumulation than a purely mechanical bounce.
Key Levels to Watch
Resistance
- 99.80–100.00: the major ceiling (99.806 on chart + the psychological 100 handle). A daily close above this zone is the clearest “trend confirmation” signal.
- 100.40–100.60: next upside supply (prior swing highs) if 100 breaks cleanly.
- 101.00–101.50: only becomes relevant if DXY transitions into a new, higher trading range.
Support
- 99.15: immediate pivot; holding above keeps the near-term recovery structure intact.
- 98.53: first meaningful “buy-the-dip” zone and former resistance shelf turned potential support.
- 97.73: key breakdown level from early December; a loss would materially weaken/negate the rebound structure.
- 96.92: the range floor; a decisive break would signal a broader regime shift lower.
S&P 500 Technical Read | Daily
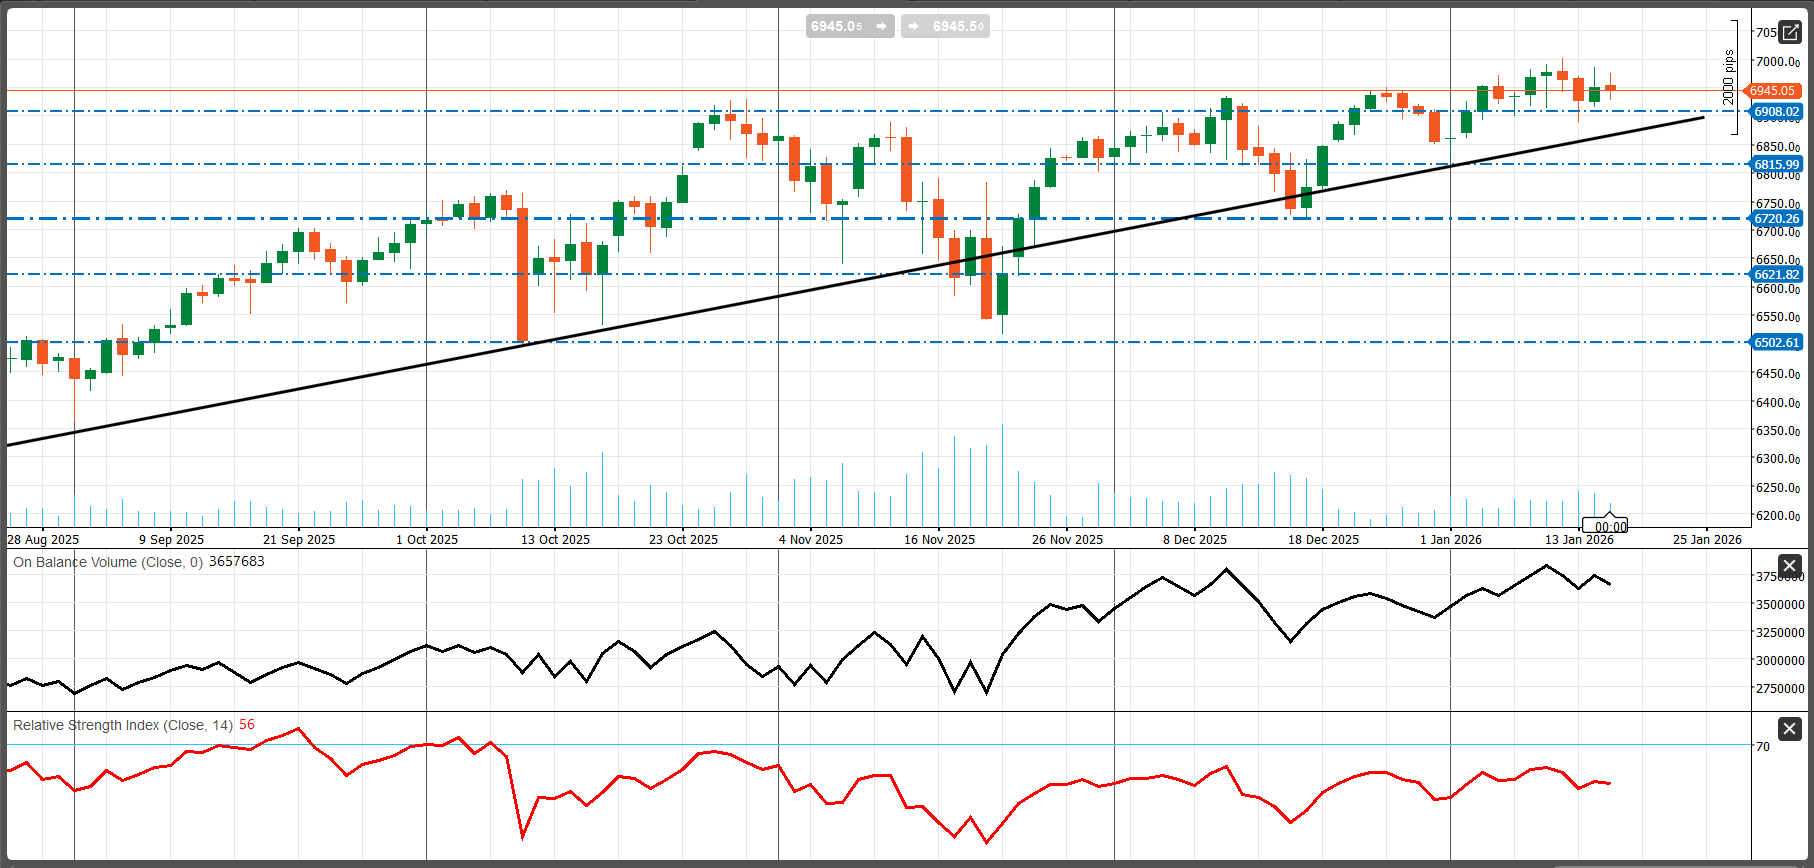
The primary trend remains up, with prices holding above the rising trendline that has guided the advance since late August. Near-term conditions, however, look like consolidation near the highs: since late December the index has been moving sideways-to-slightly higher rather than trending cleanly. This is a classic “trend + pause” setup—bulls still control the larger structure, but the market is pressing for confirmation at resistance.
Trendline Support and Structure
The rising trendline is now effectively converging with price in the high-6800s/low-6900s, creating a support confluence around 6908 and the trendline. With resistance relatively flat (~6945–7000) and support rising, the setup resembles an ascending triangle / tightening coil:
- Bulls are defending progressively higher lows.
- Sellers are repeatedly showing up near the same ceiling.
This structure often resolves with a directional breakout, but the signal quality depends on close/acceptance, not intraday probes and reversals.
Momentum and Participation (RSI + OBV)
- RSI (14) ≈ 56: constructive but not stretched—consistent with room to push higher, though not the kind of momentum that typically “steamrolls” resistance without a catalyst.
- OBV: broader uptrend remains intact, but recent action near the highs looks less decisive (flat/choppy rather than strongly rising). Participation reads as supportive, not euphoric—good for trend durability, but still compatible with a short, sharp shakeout if catalysts disappoint.
Key Levels to Watch
Resistance
- 6945: immediate ceiling / recent swing cap.
- 7000: the psychological headline level just above current price action; acceptance above it is the key confirmation.
- 7050 zone: a natural extension target if 7000 breaks and holds.
Support
- 6908: first meaningful support (recent pivot shelf + trendline confluence).
- 6816: next key support; losing 6908 often pulls price into this zone.
- 6720: major mid-range support.
- 6622: deeper support if risk-off accelerates; if this fails, 6503 becomes the structural range support.
China
China enters the week with a familiar but increasingly consequential mix: policy support is becoming more proactive, while domestic demand remains uneven and credit transmission—not liquidity availability—continues to be the binding constraint. The calendar is front-loaded with Q4 GDP and the December “activity pack” from the National Bureau of Statistics (NBS), followed shortly by a key People’s Bank of China (PBoC) policy checkpoint via the Loan Prime Rate (LPR). All of this lands against Beijing’s stated intention to maintain a “moderately loose” monetary stance in 2026.
China Economy Review — Second Week of 2026
China’s second week of 2026 delivered two clear messages: the credit pulse improved meaningfully, and trade remained a key stabilizer. At the same time, policy signals around advanced AI chips underscored Beijing’s ongoing effort to balance near-term growth support with longer-run strategic objectives. The combined picture is an economy leaning on policy-enabled financing and resilient external performance, while domestic demand appears to be improving but remains uneven across sectors.
Credit and Liquidity: Lending Rebounds, Broader Credit Is Mixed
The key surprise was a sharp year-end acceleration in new bank lending:
- New Loans (Dec): CNY 910B (vs CNY 820B expected; CNY 390B prior)
This step-up suggests banks extended credit more aggressively into year-end—often consistent with policy guidance aimed at supporting activity and stabilizing confidence. Liquidity growth also firmed:
- M2 Money Stock (YoY, Dec): 8.5% (vs 8.0% expected/prior)
Outstanding loan growth held steady to slightly firmer:
- Outstanding Loan Growth (YoY, Dec): 6.4% (vs 6.3% expected; 6.4% prior)
Total social financing (TSF) was solid versus consensus but moderated from the prior month:
- Total Social Financing (Dec): CNY 2,210B (vs CNY 2,000B expected; CNY 2,490B prior)
Interpretation: Stronger bank lending and faster money growth reinforce that financial conditions are supportive. The moderation in TSF versus the prior month suggests the improvement is not uniform across all financing channels—bank loans are doing the heavy lifting, while other forms of credit appear more variable.
Trade: Export Resilience Holds, Import Strength Is the Key Nuance
December trade data were broadly constructive:
- Trade Balance (USD, Dec): $114.10B (vs $114.30B expected; $111.68B prior)
- Exports (YoY, Dec): 6.6% (vs 3.0% expected; 5.9% prior)
- Imports (YoY, Dec): 5.7% (vs 0.9% expected; 1.9% prior)
In local currency terms:
- Trade Balance (CNY, Dec): CNY 808.80B (vs CNY 805.00B expected; CNY 792.57B prior)
Interpretation: Export resilience continues to provide an external anchor. The more important signal this week is the upside surprise in imports—often a healthier indicator for domestic demand and supply-chain activity than a surplus driven by weak import volumes. The fact that the surplus remains very large underscores that the external sector is still acting as a meaningful buffer against domestic soft patches.
Tech and Industrial Policy: AI Chip Signals Add Strategic “Guardrails”
Policy developments introduced a structural overlay to the near-term macro narrative. Beijing is reportedly working on rules to regulate how many advanced AI chips domestic firms can purchase from foreign suppliers such as Nvidia, even as demand from major Chinese technology firms remains strong and the U.S. signaled it would allow sales of Nvidia’s H200 chips to China.
Interpretation: This highlights a policy balancing act:
- Supporting near-term growth and AI deployment (strong corporate demand)
- Reducing reliance on foreign supply and managing strategic exposure
- Preserving space for domestic chipmakers to scale into incremental demand
From a macro perspective, this matters less for immediate GDP arithmetic and more for capex composition and productivity dynamics over time. Tighter guardrails on foreign chip procurement could redirect spending toward domestic alternatives and local infrastructure, but may also introduce near-term friction if demand outpaced local supply.
Bottom Line
Week two’s releases lean constructive for China’s near-term trajectory:
- Credit conditions improved, led by a strong rebound in new loans and firmer M2 growth, with loan growth steady.
- Trade remained robust, with import strength providing a more encouraging readthrough on domestic demand.
- AI chip policy signals reinforce that industrial upgrading and strategic resilience remain priority shaping where investment flows even when headline growth appears stable.
If the credit impulse and import momentum persists, the data flow would be consistent with gradual domestic stabilization supported by policy, with the external sector continuing to provide a meaningful cushion.
China Economic & Markets Outlook — Week Ahead (Jan 19–25, 2026)
1) Macro setup: headline growth vs. growth quality
China enters the week with a familiar—but increasingly market-relevant—trade-off. The core issue is not whether the economy can still deliver a respectable headline print (exports and policy support continue to keep activity supported), but whether the mix improves: firmer consumption, better private-sector credit demand, and a meaningful lift in prices from depressed levels.
A Reuters poll points to Q4 GDP around 4.4% y/y (vs 4.8% in Q3) and a slowdown to roughly 4.5% growth in 2026, reinforcing the market’s assumption that policymakers will need to keep stimulus tools active—likely via targeted measures rather than broad-based “bazooka” easing.
The credit backdrop remains the caution flag. New bank loans in 2025 fell to the lowest level since 2018, underscoring that the constraint is still demand for leverage and transmission, not liquidity availability—even as official support expands.
2) Key data: Q4 GDP + December activity (Monday)
Monday, Jan 19 (10:00 Beijing) is the primary macro event risk. The NBS is scheduled to release the National Economic Performance briefing, which typically includes Q4 GDP alongside the high-signal monthly activity set markets use to assess momentum and policy urgency.
Consensus expectations:
- Q4 2025 GDP: +1.1% q/q (SA), unchanged from the prior quarter, or roughly 4.5% y/y
- December activity: a mixed composition
- Industrial production: expected to firm to 5.0% y/y (from November)
- Retail sales: expected to decelerate further to 1.0% y/y
Even if GDP lands near consensus, implying the slowest quarterly growth since 2022—the economy would still be positioned to meet the government’s 5.0% growth target for 2025. The more important issue, in our view, is that the continued absence of broad-based fiscal stimulus aimed at materially lifting domestic demand—something authorities appear reluctant to deploy—keeps structural imbalances intact and argues for a step-down toward ~4.5% growth in 2026.
What matters most inside the release (composition over headline):
- Retail sales: the cleanest read on household demand and policy traction (subsidies, trade-ins, confidence). After sharp slowing into late 2025, markets will be highly sensitive to any re-acceleration.
- Industrial production: a gauge of export/industrial-cycle resilience and inventory dynamics.
- Fixed-asset investment (FAI) and property components: the medium-term stress point (property drag vs. infrastructure offset).
- Unemployment (often included): important for the consumption narrative and the policy reaction function.
For markets, a “better” print is not simply higher GDP—it is a shift toward consumption stabilization and less reliance on state-led investment or external demand.
3) PBoC policy preview: “moderately loose,” increasingly targeted
The PBoC has been explicit that 2026 policy will remain “moderately loose,” with willingness to use RRR cuts and interest-rate tools to keep liquidity ample and support a “reasonable rebound in prices,” while also prioritizing broad RMB stability.
What’s new this week: structural tool rate cuts take effect Jan 19
Policy is leaning further into targeted easing:
- The PBoC announced 25 bp cuts to rates on specific structural policy tools, effective Jan 19, aimed at priority areas (tech innovation, green development, financial inclusion), alongside expanded relending quotas.
This matters because it signals: easing is continuing, but via channels designed to direct credit into preferred sectors and support expectations, without immediately forcing a broad repricing of benchmark rates.
Benchmark checkpoint: Loan Prime Rate (LPR) (Tuesday)
The key scheduled policy signal is the monthly LPR fixing (often treated as the PBoC’s market-facing benchmark decision):
- Published monthly (panel-bank quotes typically submitted by the 20th; timing can shift around holidays).
- The last disclosed levels were 1-year LPR at 3.0% and 5-year LPR at 3.5%, in place until the next release.
Base case: after targeted cuts take effect on Jan 19, policymakers have a credible incentive to hold the LPR unchanged this month and preserve optionality—particularly given currency stability considerations and bank margin constraints. Markets would likely interpret an unchanged LPR as “targeted-first,” not “done.”
What would change the tone?
- Dovish surprise (LPR cut): would likely signal concern that demand and prices are not responding, or a deliberate push to accelerate mortgage/credit repricing.
- Hold + dovish bias (more likely): reinforces easing via tools (relending, RRR, liquidity operations) while keeping the benchmark structure stable.
4) Market implications: CNY, China equities, and spillovers
- CNY: If GDP/activity disappoint and the PBoC holds LPR, policy may read as cautious on broad cuts—often mildly supportive for the currency near term, with the larger driver still being global USD/rates. A surprise benchmark cut would be more likely to pressure CNY sentiment unless paired with clear stabilization evidence.
- China equities: The sustainable risk-on path typically requires better consumption read-through plus credible policy follow-through. Targeted easing can support selected themes, but broader rallies generally need confirmation that private demand and credit appetite are improving.
- Commodities/EM: Stronger-than-expected IP/FAI tends to support industrial commodities and China-linked FX; weak retail/property signals tend to do the opposite.
Practical checklist
- Mon (Jan 19): NBS National Economic Performance (Q4 GDP + December activity details).
- Tue (around the 20th): PBoC LPR—watch for confirmation of “targeted easing first” vs. broader benchmark easing.
- Policy narrative: follow-through from the Jan 19 structural tool rate cuts and any additional guidance on credit/property support.
USD/CNY Technical Analysis | Daily
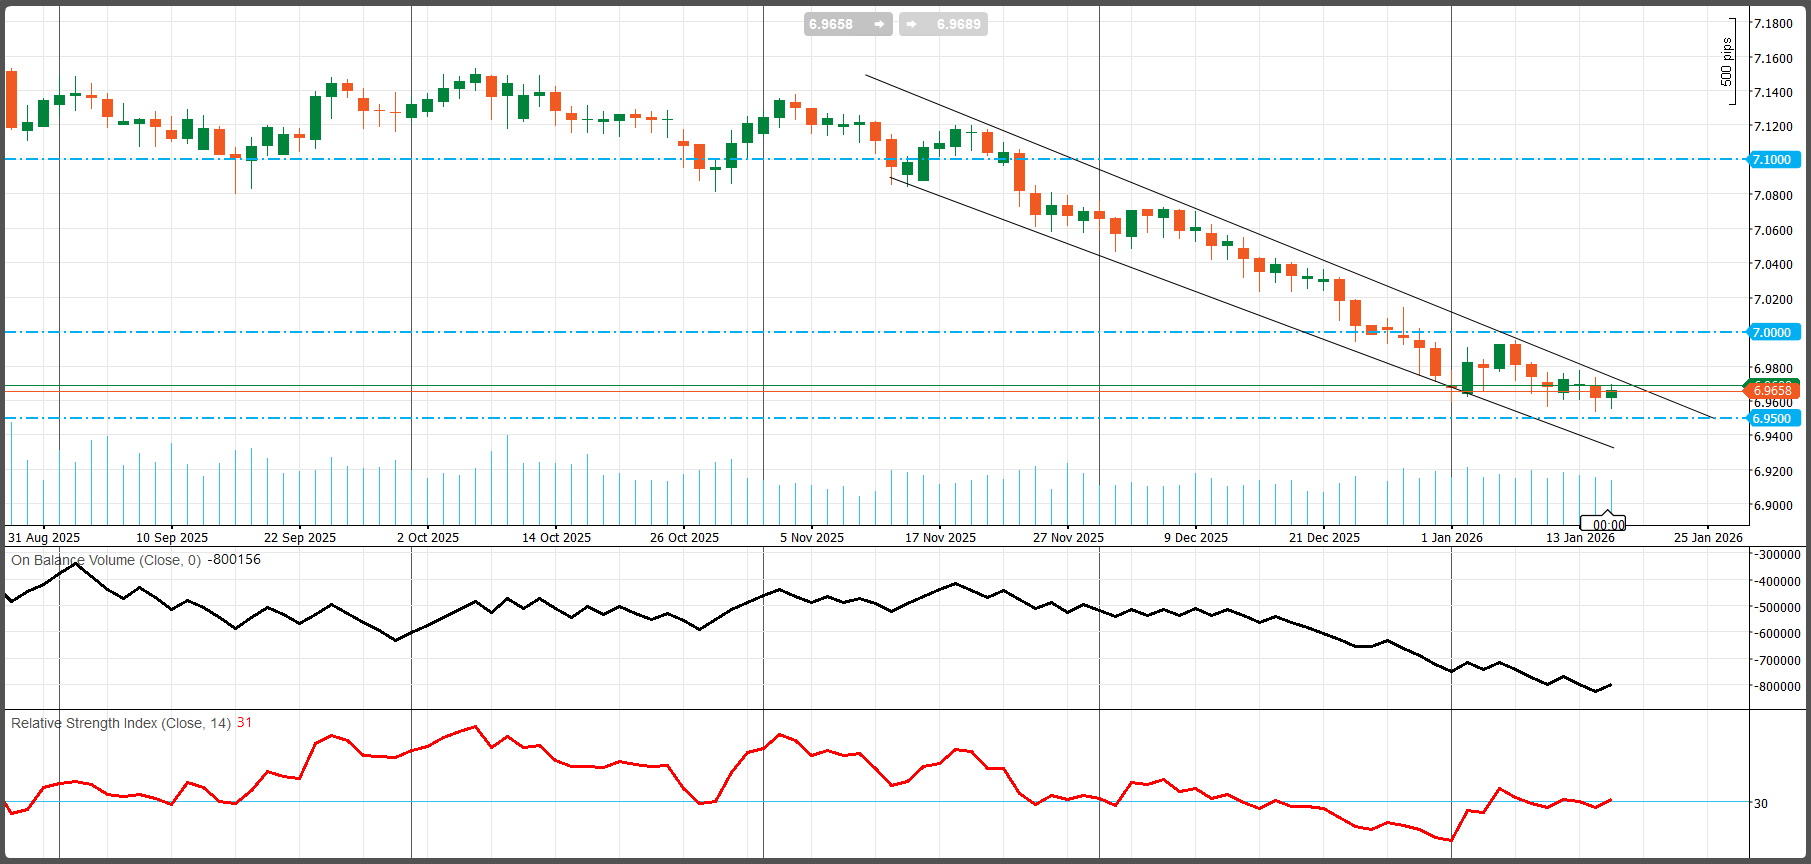
USD/CNY has remained in a clear bearish structure since mid-November, trading lower within a well-defined descending channel (lower highs and lower lows). More recently, price action has started to lose downside momentum near the channel base, with candles compressing rather than extending. That pattern often signals either (1) a developing pause/base or (2) a final flush into lower support before any meaningful mean reversion. Either way, the technical bottom line is unchanged: the trend remains down until the channel breaks to the upside and holds.
Momentum and Confirmation: Oversold Momentum, Bearish Participation
- RSI (14) ≈ 31: momentum is near-oversold, sitting just above the 30 thresholds. This increases the probability of a corrective bounce (meaning reversion), but it is not, by itself, a reversal signal.
- OBV trending lower: participation/flow remains negative, consistent with the broader downtrend and suggesting sellers have retained control on balance.
The combined read is straightforward: momentum is stretched, but flow still confirms the downtrend. That typically favors tactical bounces, while the burden of proof for a trend shift remains on the bulls.
Key Levels to Watch
Immediate pivot / balance point
- 6.965–6.97 (pivot ~6.9658): the near-term decision zone. Acceptance back above it would support a corrective rebound; failure to reclaim it keeps pressure on the channel base.
Resistance
- 7.000: major psychological level and a key horizontal pivot; a reclaim would be the first sign that sellers are losing control of the near-term tape.
- 7.100: next major resistance (prior support turned resistance); a move into/through this area would signal a more meaningful unwind of the downtrend structure.
- 7.200: upper range cap and major resistance; only relevant if price transitions from corrective bounce into broader trend reversal dynamics.
Support (downside “lines in the sand”)
- 6.950: the key horizontal support and the nearest tactical line; a clean break increases the probability of continuation lower.
- 6.930–6.920: the next logical support band if 6.95 fails (visible “air pocket” on the chart).
- 6.900: psychological support and the next headline magnet on a breakdown.
Practical Takeaway
As long as USD/CNY remains contained within the descending channel—and OBV continues to trend lower—the setup favors trend continuation with corrective bounce risk rather than a confirmed reversal. The highest signal tells are (1) whether 6.95 holds on tests and (2) whether price can reclaim 7.00 and sustain traction above it.
BoJ Week-Ahead Preview
Hold at 0.75%—but the Yen and Politics Raise the Stakes (Jan 23)
The Bank of Japan’s policy decision on Friday, January 23 comes at a delicate point in Japan’s normalization cycle. The meeting falls within the Jan 22–23 Monetary Policy Meeting window and includes the BoJ’s quarterly Outlook Report, making forecast revisions and forward guidance as market-relevant as the rate decision itself.
Baseline: policy rate held at 0.75%
Consensus expects the BoJ to keep the policy rate at ~0.75%, following the December 2025 hike to 0.75%. In December, the BoJ framed the move as part of an ongoing normalization process—explicitly signaling it would continue to raise the policy rate and adjust accommodation if the outlook is realized. That language preserves a hiking bias even if the BoJ opts to pause this week.
Two-way data signal: inflation stays firm, wages wobble
The BoJ’s reaction function still hinges on evidence of sustained, wage-led inflation. Inflation remains above the 2% target (Reuters notes it has been above target for nearly four years), which argues against any declaration that the inflation challenge is fully resolved.
Wages, however, have become a clearer source of caution. Preliminary government data showed nominal wages up only 0.5% y/y in November 2025, while real wages fell 2.8% y/y—a downside surprise that complicates the case for an early follow-up hike if it persists beyond a potential one-off distortion related to bonuses.
In practical terms: inflation argues for continued normalization; wages argue for patience.
Market pressure points: yen weakness, bond volatility, and election–fiscal risk
The main risk to a “quiet hold” is the FX and fiscal narrative, not the baseline data. Markets have increasingly priced a renewed “Takaichi trade” amid speculation around a snap election (potentially February 8) and expectations of more aggressive fiscal stimulus. This backdrop has coincided with yen weakness and a sharp move higher in long-dated JGB yields.
A weaker yen can reintroduce imported inflation dynamics (Reuters notes import-price pressure flattening after a long run of declines as the yen slid), potentially forcing the BoJ to adopt a more hawkish tone even if it leaves rates unchanged.
International scrutiny is also rising. U.S. Treasury Secretary Scott Bessent publicly urged “sound” BoJ policy and faster rate hikes to curb excessive FX volatility—an unusual external backdrop that raises the communication stakes for Governor Ueda.
What to watch on Friday (beyond the hold)
Because this is an Outlook Report meeting, markets will focus on four areas:
- Inflation and wage assumptions
- Any upgrade to inflation persistence—or stronger confidence around spring wage negotiations—would tilt guidance hawkish.
- FX sensitivity in the statement/press conference
- More explicit concern about yen-driven inflation would be read as a higher probability of an earlier hike.
- Neutral-rate framing and the “terminal” debate
- Following December’s hike, Reuters reporting highlighted market attention on how the BoJ describes the neutral-rate range and how far it intends to normalize.
- Risk balance: politics/fiscal vs. domestic demand
- If the BoJ leans more heavily on fiscal/FX risks than on wage softness, markets may pull forward tightening expectations even without immediate action.
Rate path: baseline and skew
A reasonable base case remains held in January, then one 25 bp hike in Q3 2026, consistent with the mixed data signal. However, the risk distribution is asymmetric: yen depreciation, bond-market volatility, and election/fiscal headlines raise the odds of earlier tightening signals, and potentially more than one additional hike if wage growth re-accelerates into spring.
USD/JPY Technical Analysis | Daily
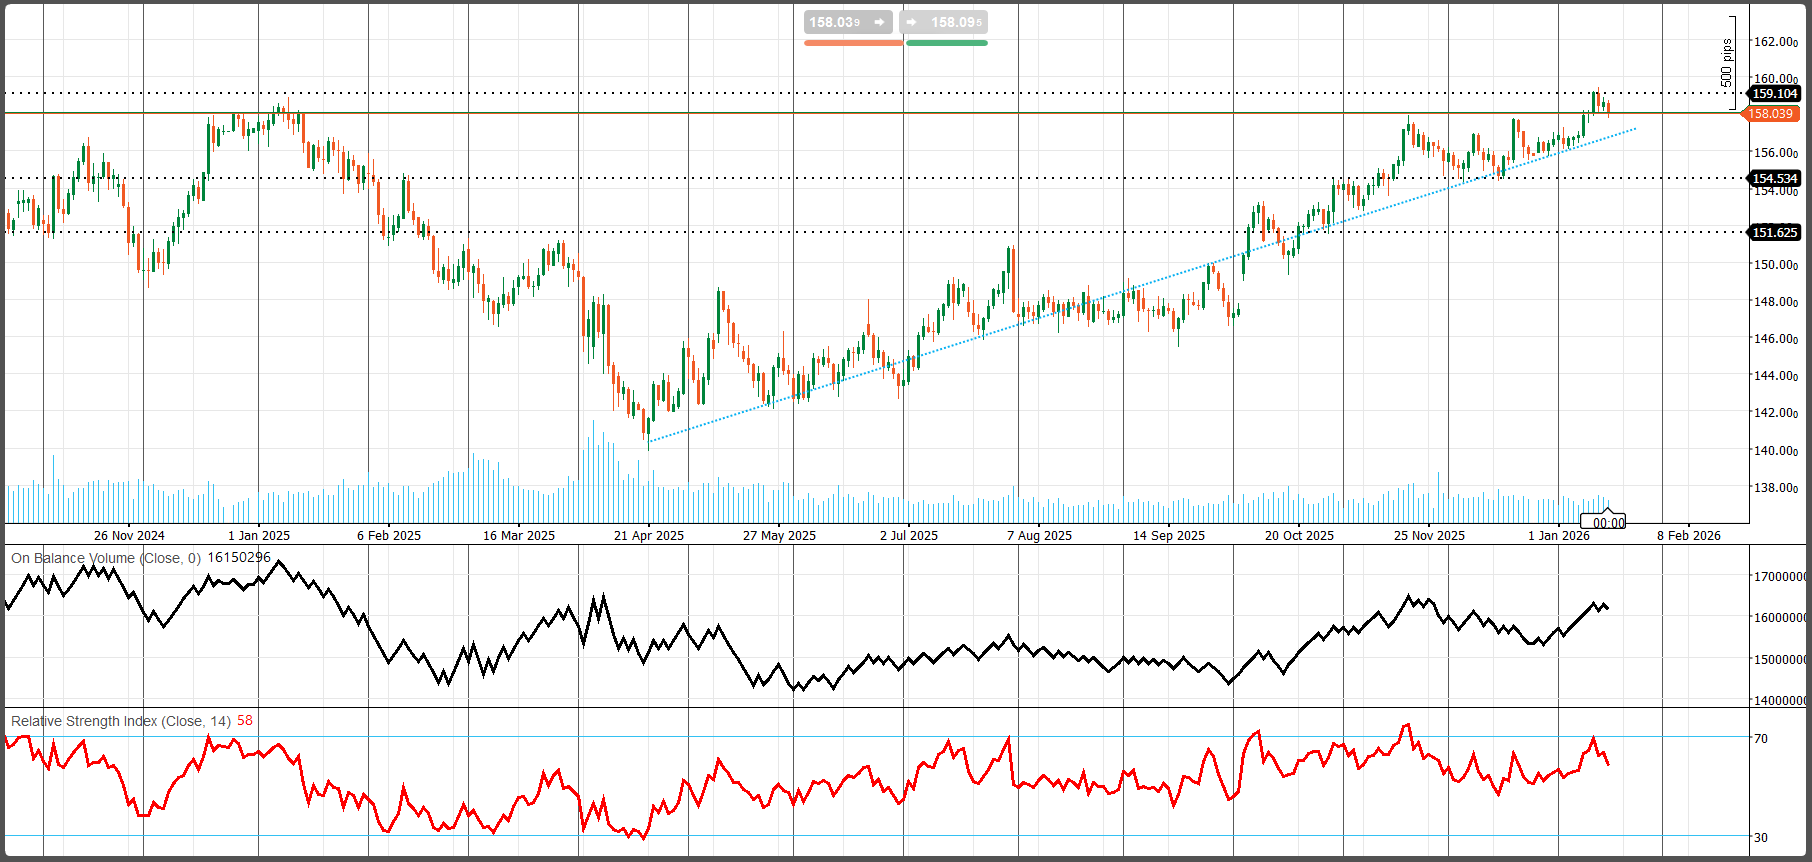
USD/JPY has remained in a firmly bullish regime since the April 2025 low, defined by a clean sequence of higher highs and higher lows and consistent respect for the rising trendline (blue). Since October, however, the character of the move has shifted: rather than a straight-line trend extension, the pair has moved into high-range consolidation, oscillating in the mid-to-high 150s while repeatedly probing the upper band near 160. In other words, the trend is still up—but the market is currently digesting gains beneath a well-defined resistance zone.
Momentum and Participation (RSI + OBV)
- RSI (14) ~58: constructive and bullish-neutral, but not overbought. This supports the broader uptrend, while also fitting a market that may need to consolidate before attempting a clean breakout.
- OBV rising into late-2025/early-2026 highs: participation remains broadly supportive of the uptrend. The most recent OBV slope is less steep, consistent with pause/absorption under resistance rather than aggressive breakout momentum.
Key Levels to Watch
Resistance
- 159.10 (159.104): the nearest supply zone and recent swing ceiling.
- 160.00: major psychological threshold and the most obvious breakout trigger; acceptance above 160 is the key confirmation signal.
- 162.00: next upside objective if 160 breaks and holds (measured follow-through zone rather than an immediate target).
Support
- 158.00: immediate short-term pivot; holding keeps the consolidation constructive.
- Trendline support (~157–158): the rising trendline is now close enough to act as a tactical “line in the sand.”
- 154.53 (154.534): major horizontal support and the key retest level for the broader uptrend structure.
- 151.63 (151.625): deeper structural support; a break below would materially weaken the larger bullish regime.
Practical Read-Through
The setup favors trend continuation with consolidation risk. Bulls generally retain control while the pair holds above 158 and the rising trendline, but a clean bullish continuation likely requires acceptance above 160, not just intraday spikes. Conversely, a failure through trendline support would shift the focus toward 154.53 as the primary retest zone for the broader uptrend.
Gold: Current Market Condition and Weekly Outlook
Gold prices slipped slightly lower Friday, slipping below the record highs touched earlier this week, as strong U.S. labor market data dampened expectations of imminent Federal Reserve rate cuts, while easing geopolitical tensions around Iran reduced safe-haven demand.
The yellow metal has retreated from a record high of $4,642.72/oz reached on Wednesday. Despite the modest pullback, bullion was still on track for a weekly gain of about 2%.
Traders assess Fed outlook after strong US data
Investor sentiment shifted after data, released on Thursday, showed U.S. initial jobless claims fell more than expected last week, underscoring the continued resilience of the labour market.
The stronger-than-anticipated reading reinforced views that the Federal Reserve may keep interest rates higher for longer, pushing market expectations for the timing of rate cuts this year.
Higher interest rates tend to reduce the appeal of non-yielding assets such as gold.
Following the data, the US Dollar Index climbed to a six-week high against a basket of major currencies, further weighing on gold prices by making the metal more expensive for overseas buyers.
Easing Iran tensions weighs on haven demand
Gold had surged earlier in the week as investors sought safety amid heightened geopolitical tensions linked to unrest in Iran.
Unrest in Iran was driven by widespread protests and government crackdowns, which had sparked fears of escalation and potential supply disruptions, lifting demand for precious metals
U.S. President Donald Trump tempered his previously hawkish rhetoric on possible military intervention, signaling a more cautious stance and noting reports that violent crackdowns on demonstrators may be easing.
Gold’s fundamental backdrop remains supportive because (i) the market is paying a premium for policy/institutional risk hedging, and (ii) central-bank buying continues to provide structural demand.
This week, the decisive variable is real yields—watch the U.S. macro sequence and PMI tone for the cleanest read-through.
Gold is trading in a strong “macro-risk + policy-credibility” regime, having recently printed record highs above $4,600/oz amid heightened concerns about U.S. institutional risk (Fed independence) and broader geopolitical stress.
Three structural supports remain dominant:
· Policy credibility / USD confidence premium
Gold has been responding to narratives that undermine confidence in monetary-policy independence—a classic catalyst for “debasement hedge” positioning.
· Persistent central-bank demand
Official-sector buying remains a major underpinning. The World Gold Council’s latest central-bank update shows continued purchases (examples cited include Poland and Brazil adding in November), reinforcing the “strategic diversification” bid.
· Geopolitical tensions
What is going on in middle east, specially the political changes in Iran, and possible political tensions in Venezuela will be the key market drivers. Higher risk, more demand for safe havens and vice-versa.
2025 performance and momentum carryover into 2026?
WGC’s market commentary highlights a powerful 2025 tape (including a strong year-end push), which matters because trend/momentum flows often persist while macro conditions stay supportive.
Offsetting factor: supply is improving at the margin—WGC-linked reporting points to global gold output tracking toward a record high in 2025, which can dampen medium-term upside if demand normalizes.
Weekly Fundamental Outlook
The core weekly question: Will the week’s macro prints and headlines reinforce falling/stable real yields and policy-risk hedging (gold-positive), or reprice yields higher and revive USD strength (gold-negative)?
What to watch: catalysts most likely to move gold
1) U.S. growth/inflation signals that move real yields
Markets are focused on releases such as U.S. personal income/spending and inflation-sensitive consumption data, plus other high-signal macro updates during the week.
For gold, the transmission is straightforward:
· Softer activity / softer inflation → real yields ease → gold supported
· Hotter activity / stickier inflation → real yields up → gold pressured
2) PMIs and “risk appetite” tone
The January “flash” PMI set is a key early read on global demand and confidence; surprises here can swing risk sentiment and rate expectations, feeding directly into gold via yields and USD.
3) Policy/institutional headlines (tail-risk premium)
Given that recent highs were linked to Fed-independence concerns, any incremental headlines in that direction can keep a risk-premium bid under gold even if data are mixed.
4) Central-bank demand narrative
With WGC data showing continued official buying, any confirmation that this trend remains firm tends to reduce downside “air pockets” on corrections.
XAUUSD Technical Analysis | Daily
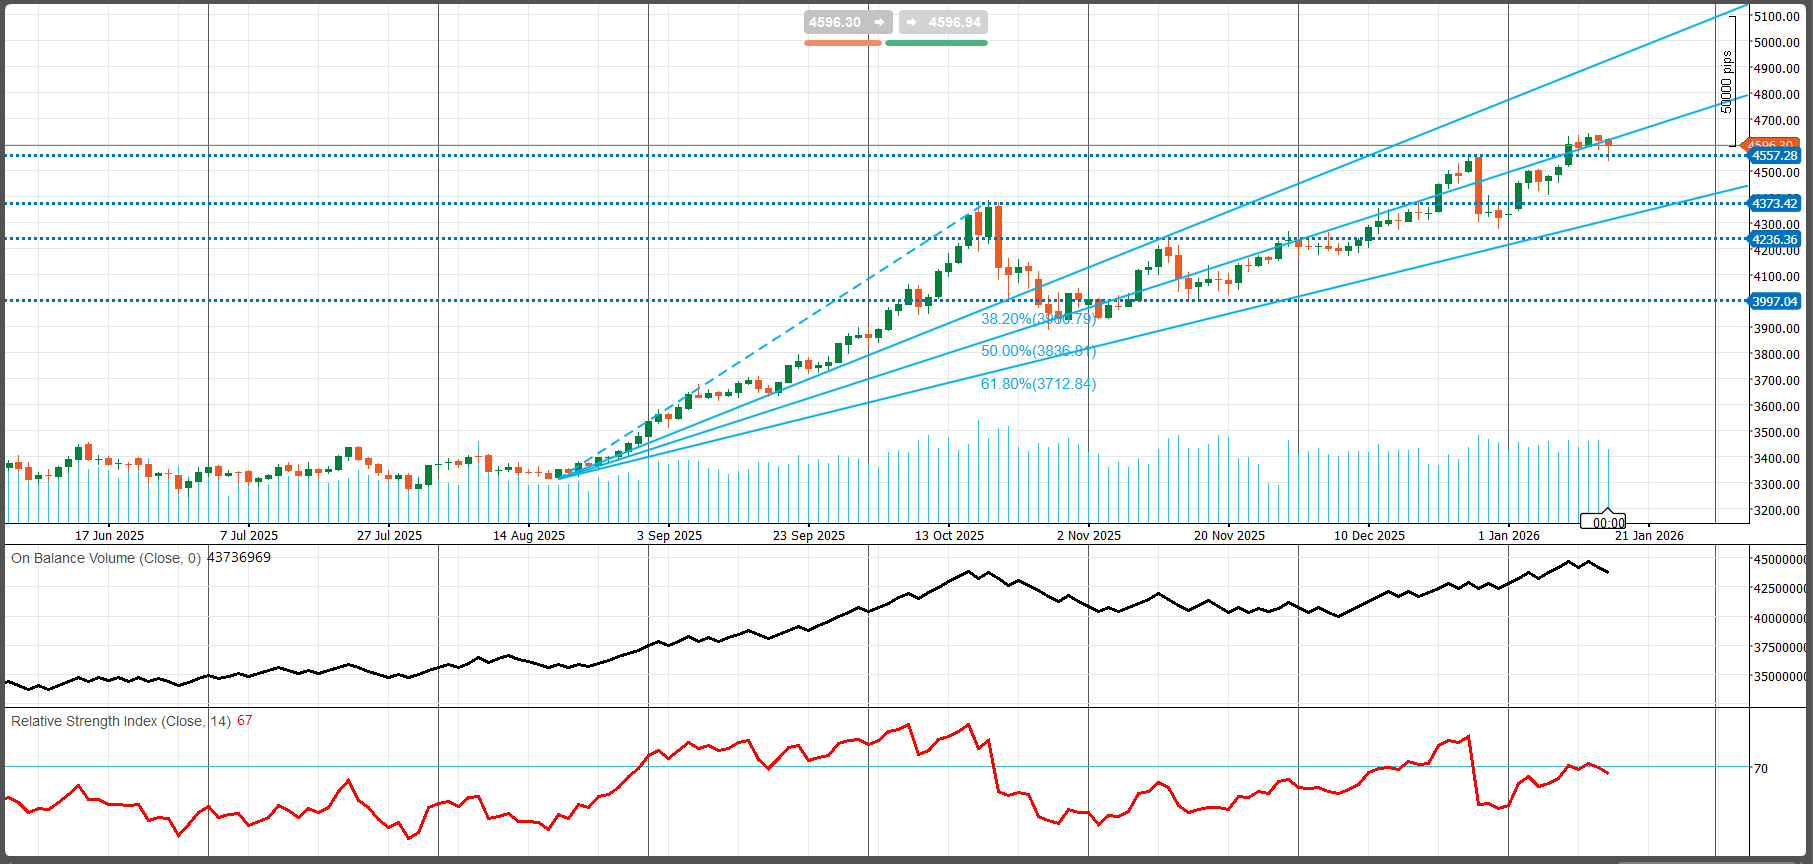
Primary trend is strongly bullish. Since the mid-August breakout, gold has been printing higher highs and higher lows inside a rising channel structure. Price is currently trading near the upper end of the advance, with the market pressing into the 4557–4600 “breakout/extension” area and holding above prior resistance—a typical late-trend posture where continuation is possible, but pullbacks can become sharper.
Momentum and participation (RSI + OBV)
RSI (14) ≈ 67: bullish momentum, near but not at the classic 70 “overbought” threshold. This supports upside pressure, but also flags late-stage extension risk (pullbacks can be fast if a rejection candle appears).
OBV is rising overall: participation confirms the uptrend. The most recent segment looks slightly choppy, consistent with distribution risk only if price stalls—but at present OBV is not screaming reversal; it is broadly supportive.
The advance is being framed by rising trendlines, and price is currently leaning toward the upper boundary. When price rides the upper channel with RSI elevated, the most common outcomes are:
Continuation breakout (strong trend persists), or
Mean reversion back toward the mid/low channel (often to the nearest horizontal pivot first—here, 4557).
Key levels to watch:
Resistance: Immediate resistance is ~4596–4600 (current price area), where the market is testing the top band; this is the “decision zone.” Above 4600, the chart opens room toward the next round numbers/extension targets (4700 → 4800 → 5000/5100) guided more by channel geometry and momentum than nearby horizontals (since price is in discovery/extension mode).
Support: 4557.28: first meaningful support / near-term pivot. A normal “cool-off” can hold here without damaging the uptrend. 4373.42: next major support shelf (prior consolidation/launch zone). And then 4236.36: secondary support; loss of 4373 would usually pull price toward this band. Lower, we have 3997.04: deeper structural support—losing this would signal a much larger regime shift (not your base case given the trend strength).
Oil Market Conditions & Weekly Outlook
Oil continues to trade under a clear macro-overhang: the market is being capped by a “2026 surplus” narrative. Mid-January price action has kept Brent in the low-$60s and WTI in the high-$50s, consistent with a forward balance that leans bearish—even as spot headlines can still generate short-lived spikes. In this regime, rallies tend to fade unless the data deliver a credible tightening impulse.
Fundamentals: balances are comfortable, and the forward curve remains skeptical
U.S. balances look seasonally steady, not tight. In the latest EIA weekly data (week ending Jan 9), commercial crude inventories increased by +3.4 mb to 422.4 mb. Refining activity stayed elevated at roughly 95% utilisation (about 17.0 mb/d of crude inputs), while the gasoline build (+9.0 mb) points to comfortable near-term product availability—an important signal that the market is not facing an acute supply squeeze.
OPEC+ remains in “stability and flexibility” mode. The eight key OPEC+ participants reaffirmed a pause in planned production increments for February and March 2026, explicitly preserving the option to extend the pause or reverse course depending on conditions. This approach effectively sets a policy floor under the market, but it does not, on its own, negate the surplus framing unless real barrels are removed.
Bullish supply signals remain headline-driven—so far. Reuters’ OPEC survey indicated December OPEC output down (around 28.40 mb/d), with declines linked to Iran/Venezuela dynamics. That can support near-term sentiment, but absent sustained disruption that reduces available exports, it has not been enough to shift the broader narrative toward structural tightness.
Medium-term guidance continues to lean bearish. The EIA’s January STEO projects global production exceeding demand with continued inventory builds, forecasting Brent around ~$56/b average in 2026 and WTI around ~$52/b average in 2026. That backdrop tends to limit rally durability unless either demand surprises materially higher or supply is removed in a lasting way.
Weekly Outlook: range-bound with a slightly heavy bias
Base case: range trade with a modest downside skew. The market is likely to fade rallies unless incoming data show a clear tightening impulse (meaningful crude/product draws, an unexpected outage, or a strong demand surprise). In practical terms, OPEC+ flexibility is the floor, while surplus expectations embedded in 2026 forecasts act as the ceiling.
The two swing factors to watch
- Inventory signals (U.S.)
- With the Monday holiday, the EIA’s Weekly Petroleum Status Report is scheduled for Thursday, Jan 22 (delayed release). This is the highest-signal input for short-horizon pricing—particularly if it confirms another crude build or reveals product tightness.
- API (Tuesday night) typically sets the tone into the official print (directional, not definitive).
- Geopolitics and the sanctions premium
- Oil remains sensitive to Iran/Venezuela/Russia headlines. However, unless disruptions reduce export availability in a sustained way, price action typically reverts back to the surplus narrative.
Practical checklist
- Tue, Jan 20: API crude/products (setup into EIA)
- Thu, Jan 22: EIA Weekly Petroleum Status Report (holiday-delayed)
- Fri, Jan 23: Baker Hughes rig count (secondary for price this week; more relevant for medium-term supply). Latest level shows oil rigs around 410.
WTI Technical Analysis | Daily
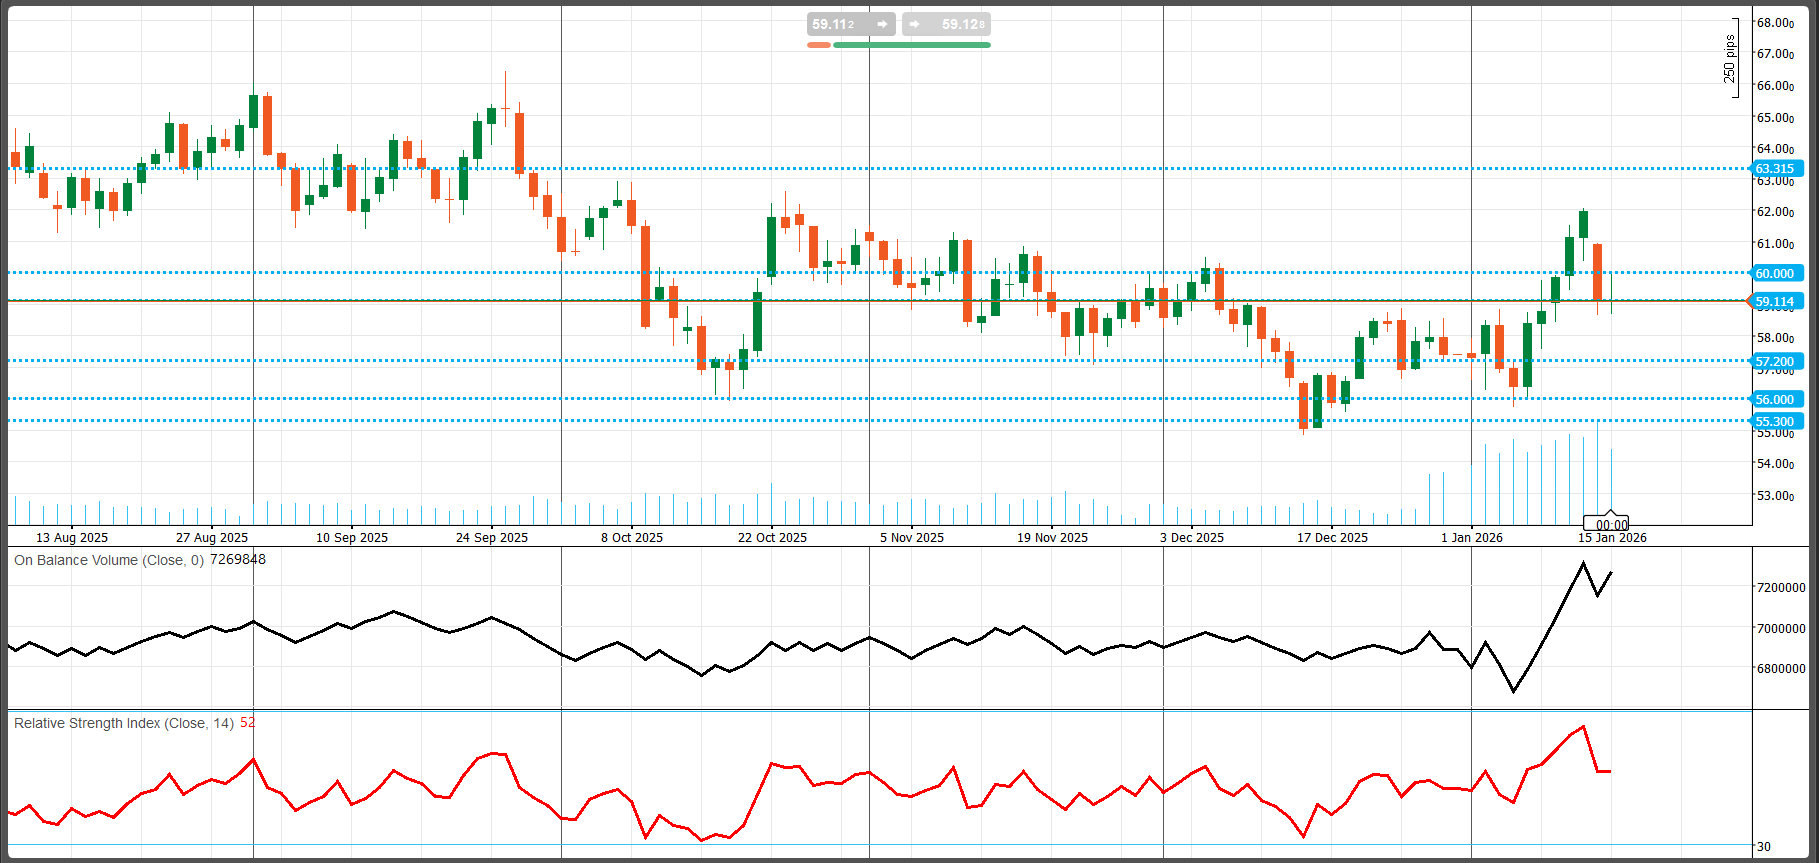
WTI remains in a broad range regime, not a clean trend. Since August/September, price has oscillated between the mid-$50s and low-$60s. The October–December leg was bearish (lower highs into the December low), followed by a January rebound that pushed toward the low-$60s before fading again. Current price around 59.11 places WTI back at a major pivot—effectively the market’s decision area between range support and resistance.
Momentum and Participation (RSI + OBV)
- RSI (14) ~52: neutral-to-slightly constructive—consistent with range trade rather than breakout conditions.
- OBV jumped sharply into mid-January: constructive participation during the rebound, suggesting more accumulation than in the prior decline. OBV has since stalled and turned choppy as price pulls back—typical when the market is deciding whether the rebound was genuine demand or a squeeze.
Key levels to watch
Resistance
- 60.00: immediate pivot. Above it, rallies can extend; below it, price often leaks back toward the mid-$50s.
- 63.315: the main upside cap (range top / repeated rejection zone). A daily close above this level would be the first credible “regime change” signal.
Support
- 59.11: current pivot zone.
- 57.20: first meaningful support below 59; often the next magnet if 59 fails.
- 56.00 and 55.30: deeper support shelf tied to the December base; this becomes the critical hold-or-break zone for the broader range.
Bottom line: The fundamental backdrop still argues for range-bound, fade-the-rally behavior unless inventories tighten meaningfully or geopolitics removes real barrels. Technically, 60 is the near-term pivot; a break higher needs acceptance and follow-through, while a loss of 59 increases the odds of a rotation back toward 57.2 and the mid-$50s base.
Cryptocurrency Market Condition and Weekly BTC Outlook
What’s driving the tape right now (fundamental)
Bitcoin enters the week with a supportive—but still headline-sensitive—backdrop. The market has regained a tangible demand anchor through institutional flow, while regulatory headlines and the rates/liquidity channel remain the dominant sources of volatility risk.
1) Institutional bid is back in focus (ETFs).
Recent reporting points to strong spot Bitcoin ETF inflows—including one of the strongest single days since October and a firm weekly pace—helping to underpin dips and improve depth on pullbacks. In the current regime, ETF flow has been the cleanest real-time “tell” for whether the market can sustain upside attempts.
2) Regulation remains a two-way catalyst.
A U.S. Senate market-structure push has periodically lifted sentiment, particularly when price action is constructive. However, the process is noisy: reports of delays or stalling have also weighed on prices and kept risk premium elevated. This creates a classic “headline beta” environment—where momentum can accelerate quickly, but reversals can be equally sharp.
3) Derivatives are improving, but not in blow-off territory.
Derivatives commentary suggests sentiment has turned more constructive, with rising open interest and a shift toward more neutral options skew versus earlier bearish bias. That profile is often consistent with a market that can grind higher but remains vulnerable to event-driven liquidations if negative headlines hit while positioning is extended.
Bottom line on market condition: BTC is supported by institutional demand (ETFs) and an improving derivatives tone, but it remains macro-sensitive (rates/liquidity) and headline-driven (U.S. regulation).
BTC Weekly Outlook
Base case: consolidation with upside optionality
With BTC trading in the mid-$90k area and catalysts skewing toward macro and policy headlines, the most likely path is range trading, with an upward bias only if ETF flows stay firm and macro conditions do not tighten materially.
What can move BTC this week
1) U.S. macro impulse (rates and USD channel)
Crypto remains highly sensitive to front-end rate repricing and real-yield swings. Even with a holiday start, the week includes multiple macro releases (income/spending, inflation-sensitive data, jobless claims, PMI) that can quickly reprice yields and broader risk appetite.
BTC translation:
- Softer activity / cooling inflation → easier yields → BTC tailwind
- Hotter data / higher yields → tighter financial conditions → BTC headwind
2) U.S. legislation / regulatory process (headline beta)
Expect fast, event-driven moves around committee actions, draft frameworks, or public statements—especially where the market interprets momentum toward clearer oversight boundaries (CFTC vs SEC) as constructive. Conversely, renewed headlines about delays or stalling can quickly weigh on crypto-linked equities and spot.
3) Flow and positioning (the breakout “tell”)
ETF inflows remain the most reliable near-term demand signal. If inflows persist, they can underpin an attempt toward $100k. At the same time, improving derivatives positioning cuts both ways: rising open interest and funding can amplify downside if a negative headline triggers an unwind.
Operating assumption: ETF flows are positive but choppy, legislation remains noisy, and macro data are mixed—favouring mean-reversion and “buy dips / sell rips” behaviour around the mid-$90k zone.
Bitcoin (BTC) Technical Analysis | Daily
Structure: downtrend broken, recovery still being tested
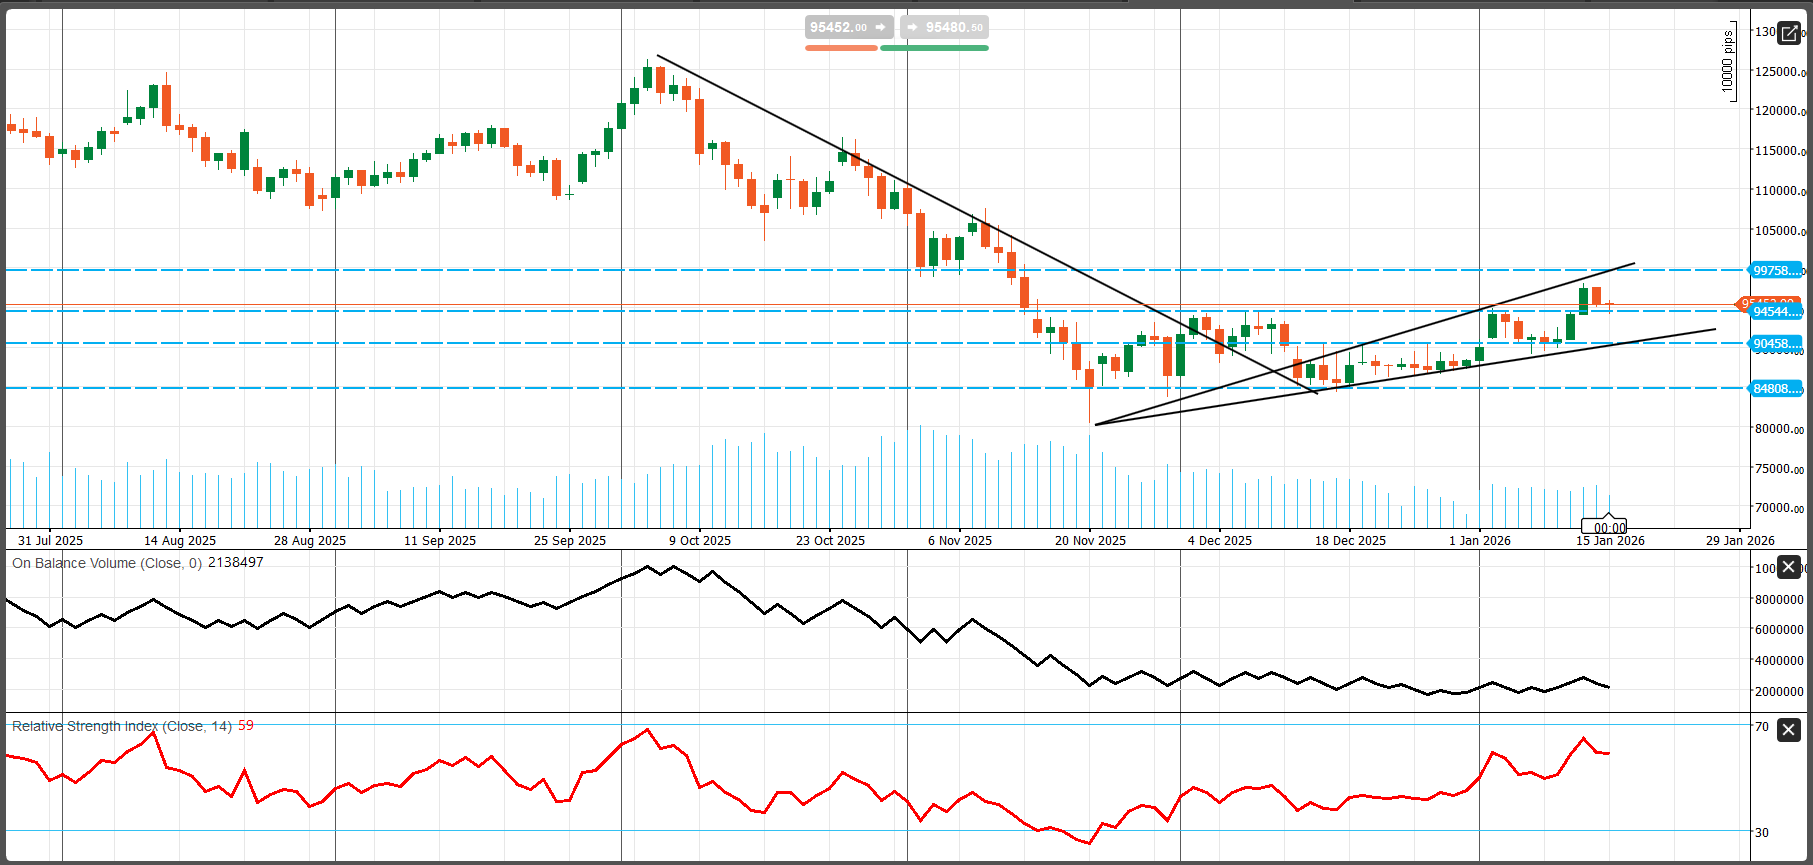
BTC topped around ~$125k (July–early October) before entering a multi-week decline that culminated in the November low near 84,808 (major swing low). From December into mid-January, price transitioned into a higher-low / higher-high recovery, climbing back into the mid-$90k area and briefly testing the upper resistance band.
The technical message is constructive: the chart reflects a bear-to-neutral/bull transition, but the recovery is still being tested by overhead supply.
Momentum and participation (RSI + OBV)
- RSI (14) ~59: bullish-leaning momentum without overbought conditions—supportive of another resistance retest if support holds.
- OBV still subdued/flat versus prior highs: participation has improved versus the selloff, but confirmation is not fully rebuilt. A sustainable breakout would ideally be accompanied by a clearer OBV pickup.
The old descending trendline from the October top has effectively been neutralized, and the post-November recovery is traveling in a rising channel / rising wedge. That is constructive while support holds—but wedges can break down if momentum fades or catalysts turn adverse.
Key levels to watch
Major resistance
- 99,758: the most important ceiling (repeated battle zone).
- 100,000: psychological level sitting directly above 99,758—acceptance/rejection here will be critical even if it is not explicitly marked.
Immediate pivot / inflection
- 95,444: the current battlefield level. Holding above it keeps the recovery structure intact.
Major supports
- 90,458: next high-probability downside magnet if 95,444 breaks (prior structure support).
- 84,808: the structural floor of the entire move; a break would confirm a materially more bearish regime.
Bottom line: Technically constructive, fundamentally supported by ETF flows—but still highly sensitive to macro and U.S. policy headlines. The market remains in a consolidation regime unless it can clear 99,758/100k with convincing participation and follow-through.
Comments