 English
 پارسی


Watch the Video
Global Markets Outlook Week 24
Under Pressure as U.S. Data, Oil Risk, and Inflation Fears Drive Sentiment
Global markets enter the week of June 8–14, 2026, with a more cautious and defensive tone after a sharp shift in investor sentiment. The previous week showed that the global economy is not collapsing, but markets are now dealing with a more difficult mix of strong U.S. data, higher Treasury yields, stronger dollar demand, oil-price risks, geopolitical uncertainty, and heavy profit-taking in technology stocks. The main message for investors is clear: growth remains resilient in some regions, but inflation and rate risks have returned as the dominant market drivers.
The United States remains the center of global market direction. The latest U.S. jobs report was much stronger than expected, with nonfarm payrolls rising by 172,000, far above the 85,000 forecast, while the unemployment rate held steady at 4.3%. Wage growth was firm but not extreme, with average hourly earnings up 0.3% month-on-month, while annual wage growth slowed to 3.4%. This confirmed that the U.S. labor market remains resilient despite higher energy prices and geopolitical stress.
However, strong labor data also changed the market’s view of the Federal Reserve. Investors moved toward a more hawkish Fed outlook, with higher expectations that rates may need to remain restrictive for longer or even rise later in 2026. Treasury yields jumped after the jobs report, with the 2-year yield at 4.115% and the 10-year yield at 4.53%. The U.S. Dollar Index also climbed to around 100.06, its highest level since early April, gaining about 1.2% for the week. This stronger dollar and higher-yield environment pressured gold, crypto, emerging-market assets, and high-duration equities.
Wall Street faced a major reversal. The S&P 500 ended its nine-week winning streak, falling 2.64% on Friday, while the Nasdaq Composite dropped 4.18%, its worst one-day decline since April 2025. The selloff was concentrated in technology and semiconductor stocks, where positioning had become stretched after the AI-led rally. The Philadelphia Semiconductor Index suffered its largest one-day percentage decline since March 2020, wiping out more than $1 trillion in market value. The AI trade is not necessarily broken, but the correction showed that high valuations are vulnerable when yields rise.
For the week ahead, the most important U.S. event will be CPI on Wednesday, June 10. A hotter inflation reading would likely strengthen the case for a more restrictive Fed, support the dollar and Treasury yields, and add pressure on equities, gold, crypto, and emerging-market currencies. A softer CPI print could help markets stabilize after last week’s selloff. The next key release will be PPI on Thursday, June 11, which will show whether higher oil, transport, and supply-chain costs are moving into broader pipeline inflation.
Energy remains one of the biggest global risks. Brent crude settled at $92.89, while WTI closed near $90.25 on Friday. Both benchmarks still posted weekly gains, with Brent up 0.9% and WTI up 3.2%, as hopes for a quick U.S.-Iran peace deal faded. The Strait of Hormuz remains heavily restricted, keeping energy flows through the Persian Gulf under pressure. Tight refined product inventories and large U.S. crude stock draws also supported oil prices. If oil remains above $90, inflation expectations may stay elevated and complicate policy decisions for the Fed, ECB, BOJ, and emerging-market central banks.
Europe enters the week with weak growth momentum and major policy risk. Eurozone GDP contracted 0.2% quarter-on-quarter in Q1 2026, while annual growth slowed to 0.3%. Ireland’s 12.1% GDP plunge weighed heavily on the regional figure. The euro fell around 0.7% to nearly $1.1525, pressured by weak growth and a stronger U.S. dollar. The ECB meeting on June 11 will be critical. Markets broadly expect a 25-basis-point rate hike, but the bigger issue is whether the ECB signals more tightening later this year. A hawkish ECB could support the euro in the short term, but it may also hurt European equities if investors fear tightening into weak growth.
The UK also looks fragile. Construction activity remains deeply weak, with the S&P Global Construction PMI falling to 38.2. Housing data also softened, with Halifax house prices down 0.1% month-on-month and annual growth slowing to 0.5%. Mortgage rates remain high at 6.60%, keeping affordability under pressure. Sterling fell about 0.7% to around $1.3335, mainly because of dollar strength, but weak domestic data also offered little support.
Japan is becoming a key policy and FX risk. Domestic data improved, with stronger household spending, better wages, and firmer leading indicators. But this also increased speculation that the Bank of Japan may discuss raising rates later in June. The yen weakened beyond 160 per dollar, raising intervention risk. Japanese equities came under pressure, with the Nikkei 225 down 1.6%, led by local technology and chip stocks. In Week 24, USD/JPY will be highly sensitive to U.S. yields, intervention headlines, and BOJ communication.
China and broader Asia show mixed signals. Mainland Chinese markets were relatively stable, while Hong Kong and regional chip-heavy markets weakened due to technology profit-taking. China’s domestic AI and semiconductor themes remain supportive, but the economy still faces external risks from high oil prices, weaker global tech sentiment, and stronger dollar pressure. China’s crude imports also fell sharply between February and May, increasing focus on energy security.
Emerging markets face a tougher global backdrop. India remains one of the stronger stories, with GDP growth of 7.8% year-on-year in Q4 and stable policy from the Reserve Bank of India, which kept rates unchanged at 5.25%. However, broader emerging-market assets are vulnerable to higher U.S. yields, a stronger dollar, oil volatility, and weaker global risk appetite. Turkey remains inflation-sensitive, with annual CPI at 32.61% and PPI at 28.93%, while South Africa faces reserve and currency pressure.
Gold starts the week under pressure. After falling sharply after the U.S. jobs report, gold is trading more like a rate-sensitive asset than a pure safe haven. Higher yields and a stronger dollar remain the biggest headwinds. XAUUSD needs softer U.S. inflation data or stronger geopolitical safe-haven demand to recover. Below $4,370, gold remains vulnerable, with key support around $4,300.
Crypto remains one of the weakest areas of global risk assets. Bitcoin briefly fell below $60,000, reached its lowest level since October 2024, and was heading for a weekly loss of more than 16%. Spot Bitcoin ETFs saw around $1.4 billion in outflows, marking the fourth straight week of more than $1 billion in withdrawals. Strategy’s rare Bitcoin sale, rising rate expectations, and capital rotation damaged sentiment. Bitcoin needs to reclaim $63,500–$65,000 to improve the short-term outlook, while a break below $59,000 could open deeper downside.
Overall, Week 24 will be defined by whether inflation data confirm or challenge the hawkish repricing triggered by strong U.S. labor data. The base case is elevated volatility and selective risk-taking. A softer U.S. CPI and PPI combination could trigger a relief rally, weaken the dollar, and help equities, gold, and crypto stabilize. But hot inflation, weak Treasury auction demand, renewed Middle East escalation, higher oil prices, or continued semiconductor selling would likely keep markets defensive. The global economy is entering a more complex phase, where investors must be selective because growth resilience, inflation risk, energy disruption, stronger dollar pressure, and stretched technology positioning are all moving markets at the same time.
U.S. Economic Outlook for Week 24:
Strong Jobs, Sticky Inflation Risk, and Fed Policy Pressure
The U.S. economy enters the week of June 8–14, 2026 with a stronger growth profile but a more complicated market backdrop. Recent data showed that the economy is still resilient, especially in the labor market and manufacturing sector, but inflation risk has returned as the central concern for investors. The main market debate has shifted from “will growth slow?” to “will strong growth, higher oil prices, and sticky inflation force the Federal Reserve into a more hawkish policy stance?”
The key trigger was the May jobs report. Nonfarm payrolls rose by 172,000, far above the 85,000 forecast, while the unemployment rate stayed unchanged at 4.3%. Wage growth remained firm, with average hourly earnings rising 0.3% month-on-month, while annual wage growth slowed to 3.4% from 3.6%. This combination shows that the labor market is not overheating aggressively, but it is still strong enough to keep pressure on the Federal Reserve. For markets, that means rate-cut expectations have weakened, while the possibility of a rate hike later in 2026 has become more meaningful.
Other labor indicators also confirmed that the job market is softening only at the edges. April job openings increased to 7.618 million, the highest level since May 2024, while initial jobless claims rose to 225,000. Claims were higher than expected, but not high enough to suggest a serious labor-market breakdown. Overall, the employment side of the Fed’s mandate remains stable, which means inflation data will now carry more weight in shaping policy expectations.
The manufacturing sector also delivered a stronger signal. The ISM Manufacturing PMI rose to 54.0 in May, beating expectations and reaching its highest level in four years. However, the prices-paid index remained very high at 82.1, showing that input-cost pressure is still a major issue. This matters because higher energy prices, the Iran conflict, and disruption around the Strait of Hormuz could push costs higher across transportation, production, and supply chains.
Productivity data added another concern. Nonfarm productivity rose only 0.3% quarter-on-quarter in Q1, below expectations, while unit labor costs increased 1.8%. Slower productivity combined with resilient wages can keep inflation pressure alive, especially if companies face higher input costs and pass them on to consumers.
Markets reacted sharply to this mix of strong growth and inflation risk. Treasury yields rose after the jobs report, with the 2-year yield at 4.115% and the 10-year yield at 4.53%. The U.S. Dollar Index climbed to 100.06, its highest level since early April, and gained around 1.2% for the week. Higher yields and a stronger dollar pressured gold, crypto, and high-duration equities.
Wall Street also suffered a major reversal. The S&P 500 ended its nine-week winning streak, falling 2.64% on Friday, while the Nasdaq Composite dropped 4.18%, its worst daily decline since April 2025. The selloff was concentrated in technology and semiconductors, where positioning had become stretched after the AI-led rally. The Philadelphia Semiconductor Index posted its largest one-day percentage decline since March 2020, erasing more than $1 trillion in market value.
This does not mean the AI investment theme is over. It does mean that valuations are now more sensitive to interest rates. If yields continue rising, high-growth technology and semiconductor stocks may remain under pressure. If yields stabilize, quality AI and infrastructure names could attract buyers again after last week’s sharp correction.
The most important event for the week ahead is May CPI on Wednesday, June 10. This release will be decisive before the Fed’s June policy meeting. Markets will focus on both headline and core inflation. A hotter CPI print would reinforce the view that the Fed may need to stay restrictive for longer or even move toward a hiking bias. That would likely support the dollar and Treasury yields while pressuring equities, gold, crypto, and emerging-market assets.
Inflation risks are closely tied to energy. The Consumer Price Index is estimated to have risen 0.52% in May, pushing annual inflation to a possible three-year high of 4.2%. Energy goods, mainly gasoline, are estimated to have jumped 8%, while food prices likely rose 0.3%. Excluding food and energy, core prices are estimated to have risen a more moderate 0.23%, but some pressure may appear in used autos and airline fares. Airline fares are expected to rise around 3%, partly because of higher jet fuel costs.
Shelter inflation is expected to move back toward a 0.2%–0.3% monthly pace, while core services excluding shelter and travel are expected to remain near a 2.5% six-month pace, broadly in line with the pre-COVID trend. This suggests inflation is not accelerating everywhere, but energy and transport costs remain enough to keep the Fed cautious.
The second major release will be May PPI on Thursday, June 11. Producer prices matter because they show whether higher energy, transport, and supply-chain costs are feeding into business input prices. A strong PPI report would suggest inflation pressure is building beyond consumer prices and would likely be negative for bonds and growth stocks. Weekly jobless claims on the same day will also matter. If claims remain near recent levels, markets may conclude the labor market is still too firm for the Fed to ease.
The University of Michigan Consumer Sentiment report on Friday, June 12, will also be important, especially inflation expectations. If consumers expect higher inflation, markets may treat it as another hawkish signal. If expectations ease, some of the pressure created by the strong jobs report could fade.
Treasury auctions are another key risk. The market will absorb 3-year, 10-year, and 30-year Treasury supply during the week. Weak auction demand could push yields higher and renew pressure on technology stocks. Strong demand could calm the bond market and support a relief rally.
Energy remains a major macro variable. Brent crude ended near $92.89, while WTI settled around $90.25. Oil is still supported by geopolitical risk, tight supply conditions, and disruption around the Strait of Hormuz. If oil remains above $90, inflation expectations may stay elevated, making the Fed’s job harder.
For markets, the base case is elevated volatility. A hot CPI and strong PPI combination would likely lift yields and the dollar, pressure gold and crypto, and keep the Nasdaq vulnerable. A softer CPI with stable jobless claims would be the best setup for a relief rally, especially if Treasury auctions show solid demand. However, if inflation cools while consumer sentiment weakens sharply, markets may shift from inflation fear to growth concern.
Overall, the U.S. economy enters Week 24 with solid growth signals but rising policy risk. Strong jobs data reduced recession fears, but they also increased the risk of tighter Fed policy. Until CPI, PPI, consumer sentiment, and Treasury auction results are clear, traders should expect volatility across equities, bonds, the dollar, gold, oil, and crypto.
Wall Street and U.S. Dollar Outlook:
Strong Jobs Data Revives Fed Risk and Breaks the Tech Rally
Wall Street and the U.S. dollar enter the week of June 8–14, 2026 at a critical turning point. The previous week ended with a sharp market repricing after stronger-than-expected U.S. labor data revived expectations that the Federal Reserve may need to keep policy restrictive for longer or even raise interest rates later in 2026. The market narrative has clearly shifted from AI-led optimism and stable rates toward strong U.S. growth, sticky inflation risk, higher Treasury yields, and a more hawkish Fed path.
The main trigger was the May jobs report. U.S. nonfarm payrolls increased by 172,000, well above the 85,000 forecast, while the unemployment rate remained steady at 4.3%. Average hourly earnings rose 0.3% month-on-month, showing that wage growth is not extreme but still firm enough to matter for inflation expectations. For investors, this was a double-edged signal: the U.S. economy still looks resilient, but the Federal Reserve now has less reason to cut rates and more reason to stay cautious.
Treasury yields reacted quickly. The 2-year yield rose to 4.115%, while the 10-year yield climbed to 4.53%. This higher-yield environment strengthened the U.S. dollar and pressured rate-sensitive assets. The U.S. Dollar Index rose to 100.06, its highest level since early April, and gained around 1.2% for the week. Dollar strength was supported by three key forces: resilient U.S. data, higher yields, and safe-haven demand linked to the Middle East conflict.
Wall Street suffered a major reversal. The S&P 500 ended its nine-week winning streak, closing at 7,383.74 after falling 2.64% on Friday. The Nasdaq Composite dropped 4.18% to 25,709.43, its worst one-day decline since April 2025. The Dow Jones Industrial Average fell 695.15 points, or 1.35%, to 50,866.78. The selloff was heavily concentrated in technology and semiconductor stocks, where positioning had become stretched after the strong AI-led rally.
The semiconductor sector was hit especially hard. The Philadelphia Semiconductor Index posted its largest one-day percentage decline since March 2020, erasing more than $1 trillion in market value. Nvidia fell 6.2%, while Intel, Micron, AMD, and Broadcom dropped between 7.9% and 13.3%. The move does not mean the AI bull market is over, but it shows that valuation and positioning risk are now much higher. If yields continue rising, high-duration technology and semiconductor stocks may remain under pressure.
The key event for the week ahead is U.S. CPI on Wednesday, June 10. A hotter inflation report would likely confirm the hawkish message from the jobs report, support the dollar, push Treasury yields higher, and keep pressure on the Nasdaq, semiconductors, gold, and crypto. A softer CPI print would provide room for a relief rally by reducing fears of an imminent Fed policy shift.
U.S. PPI on Thursday, June 11, will also be important. Markets want to know whether higher energy, transport, and supply-chain costs are feeding into broader producer inflation. Strong PPI would support the dollar and hurt high-valuation equities, while softer PPI could help stabilize risk sentiment. Treasury auctions will also matter, as weak demand for 3-year, 10-year, and 30-year supply could push yields higher again.
For the U.S. dollar, the short-term bias remains bullish while DXY holds above 100.00. Hot CPI or PPI could push the index toward 100.50–101.00, while a move above 101.00 would confirm stronger upside momentum. If inflation data come in softer, DXY could pull back toward 99.50. However, as long as yields stay elevated and geopolitical risks remain active, dollar downside may be limited.
Major currency pairs remain vulnerable to dollar strength. EUR/USD stays weak below 1.1600, especially after poor Eurozone GDP data. GBP/USD may struggle below 1.3400 because UK domestic data remain soft. USD/JPY remains supported by rate differentials, but trading above 160 is risky because Japanese intervention headlines could trigger sharp reversals.
Overall, the base case for Week 24 is a stronger dollar and volatile Wall Street. If inflation data cool and yields stabilize, equities could stage a relief rally led by quality AI and technology names. But if CPI or PPI are hot, yields rise further, and DXY moves above 101, Wall Street could extend losses. Until the inflation data are clear, the dollar remains favored over high-duration risk assets.
USD Technical analysis
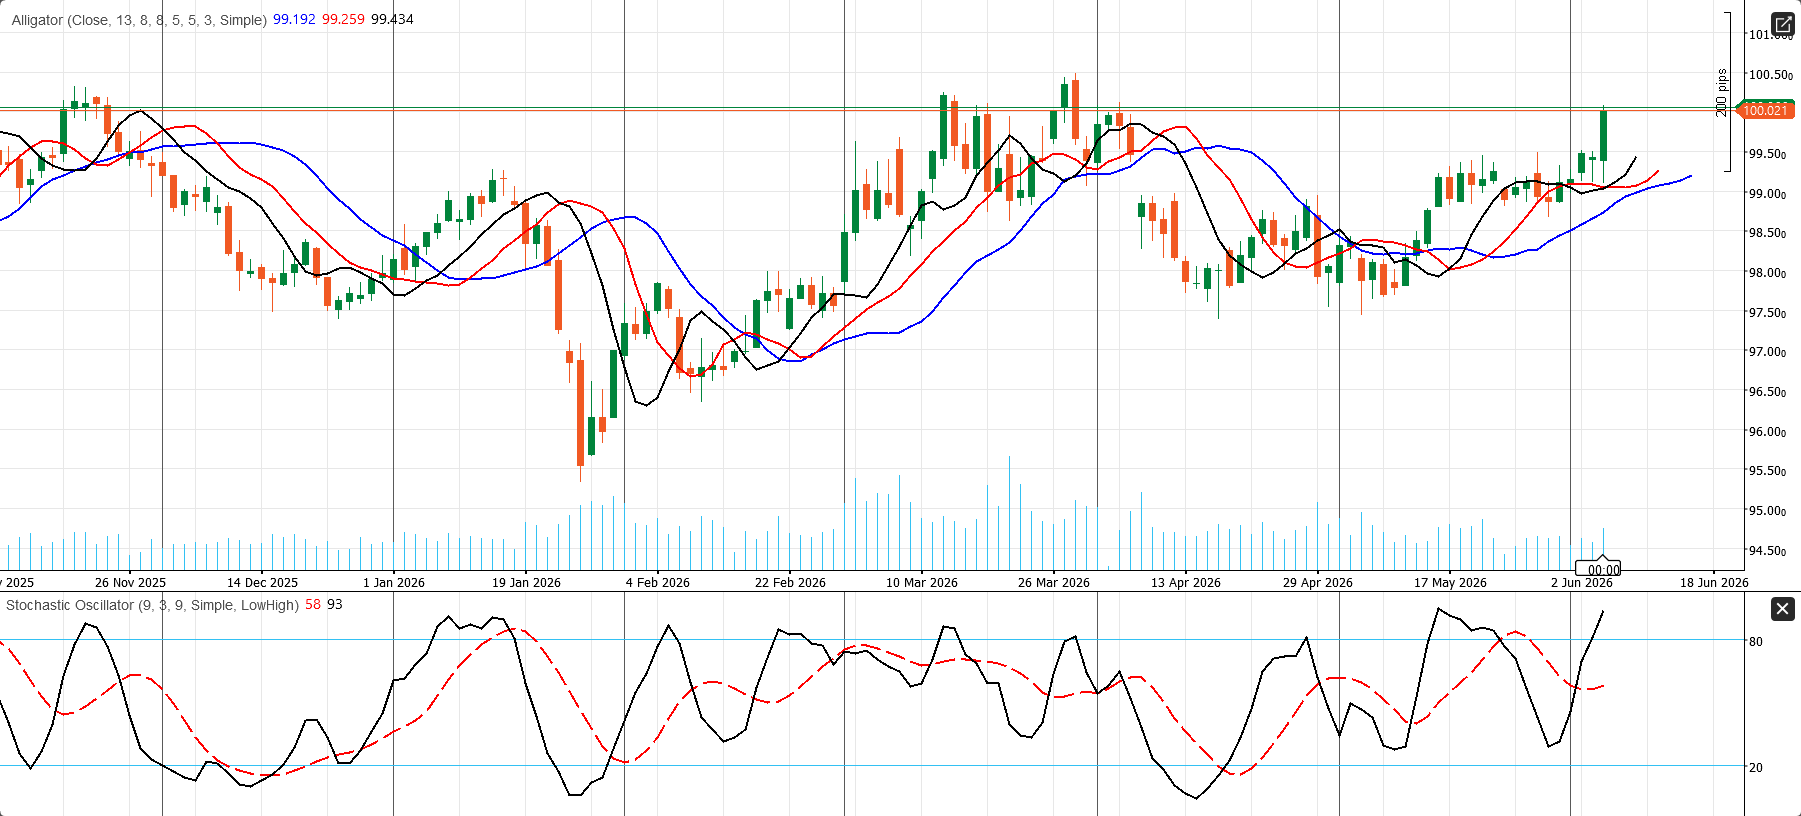
The daily U.S. Dollar Index (DXY) chart has turned constructive again. Price is trading near 100.021, above the full Alligator cluster, with the slower lines holding around the 99.19–99.43 zone. That structure shows the short-term trend has shifted back in favor of buyers after the earlier consolidation phase.
Technically, the key level now is the 100.00–100.02 resistance area. A firm daily close above that zone would confirm continuation and expose the next upside levels near 100.50 and then 101.00. On the downside, the first support sits around 99.43, followed by 99.25, while the broader trend floor comes in near 99.19. As long as DXY remains above the Alligator cluster, the bias stays mildly bullish.
Momentum is positive but not fully clean yet. The stochastic oscillator has turned sharply higher and is moving toward the upper zone, which signals renewed upside pressure, but it also warns that the index is approaching a short-term overbought area. In practical terms, this is a bullish chart pressing resistance, not yet a fully confirmed breakout.
S&P 500 Technical Analysis
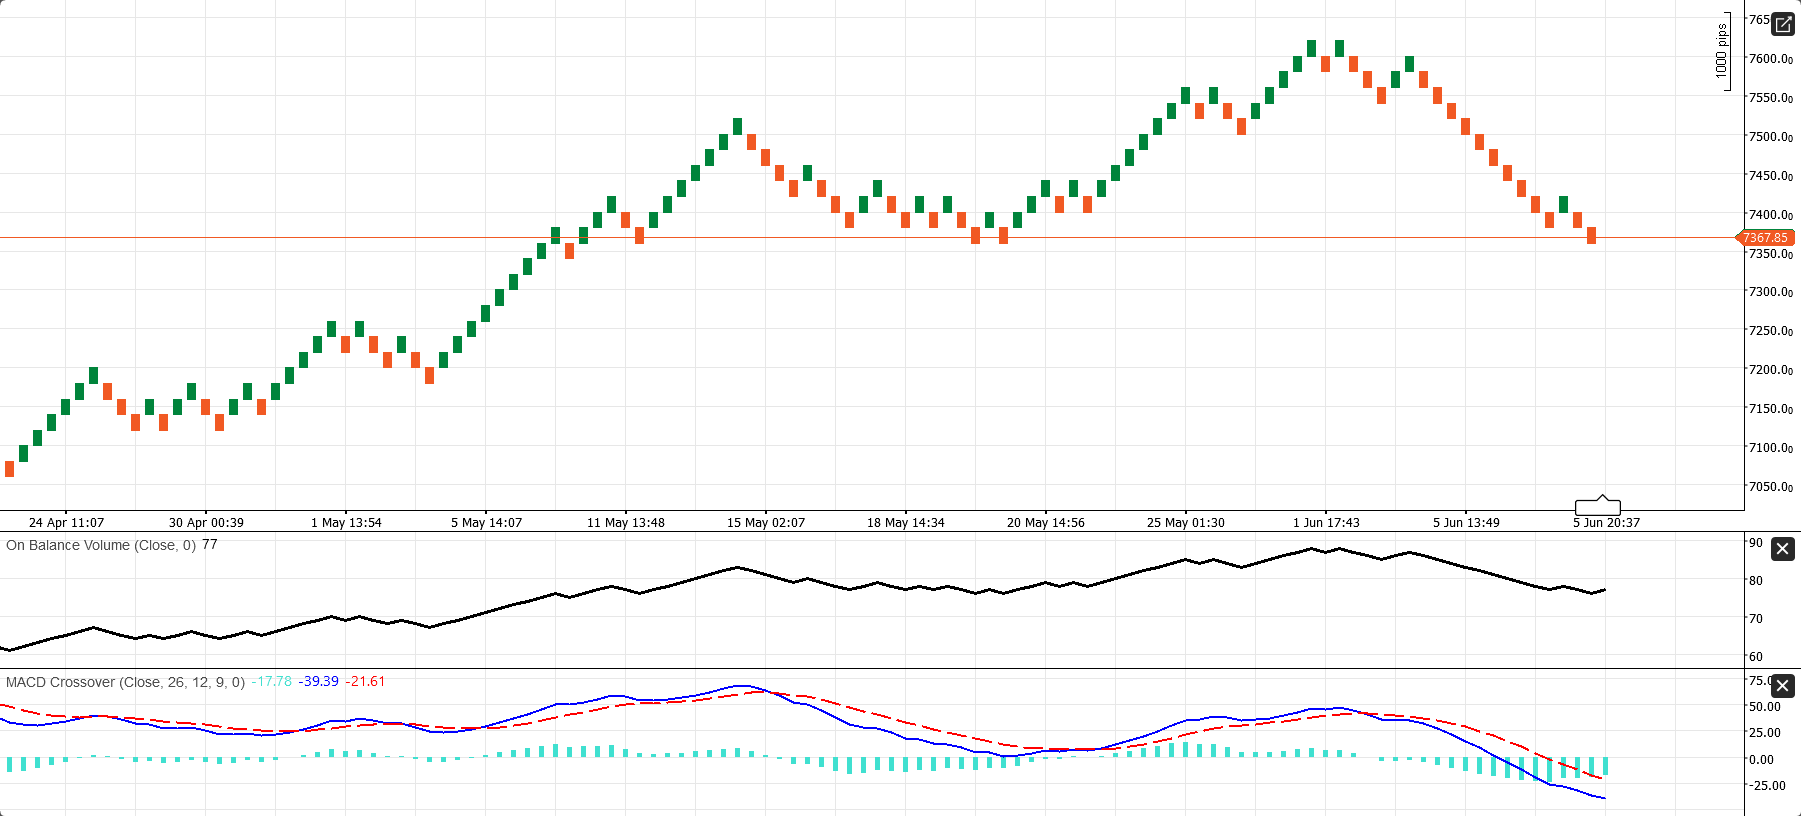
The daily S&P 500 / US500 chart has lost upside momentum after failing to hold the recent peak zone around 7,600–7,620. Price is now trading near 7,367.85, and the latest candle structure shows a clear corrective downswing from the June high. The immediate pivot is 7,368. As long as price remains below the recent rebound highs, the short-term tone stays pressured.
From a price-structure perspective, the first resistance now sits near 7,420–7,450, followed by the more important supply zone around 7,550–7,620. On the downside, the first support comes in around 7,300, and if that level gives way, the next broader downside area is near 7,200. The chart no longer looks like a clean trend continuation setup. Instead, it looks like a pullback phase after an extended rally.
The supporting indicators also lean softer. On-Balance Volume has rolled over from its recent highs, which suggests participation has weakened during the decline. At the same time, the MACD structure has turned negative, with the histogram below zero and the MACD line still under the signal line. In practical terms, this is not a panic chart, but it is a chart where momentum favors sellers unless price can reclaim the 7,420–7,450.
Eurozone Economic Outlook:
Weak Growth, ECB Rate Risk, and Energy Pressure Shape Week 24
The Eurozone enters the week of June 8–14, 2026 in a fragile macro position. Growth momentum is weakening, consumer demand is soft, bond yields are rising, and energy-related inflation risks are again complicating the European Central Bank’s policy outlook. The region is not in a deep crisis, but the latest data show that the recovery is uneven and vulnerable to external shocks, especially higher oil prices, a stronger U.S. dollar, and renewed geopolitical risk.
The clearest warning came from the latest Eurozone GDP report. The economy contracted 0.2% quarter-on-quarter in Q1 2026, missing expectations for 0.1% growth and reversing the previous 0.1% expansion. Annual GDP growth slowed sharply to 0.3%, below the 0.8% forecast and down from 1.2% previously. The decline was partly distorted by a sharp 12.1% drop in Ireland’s GDP, but the broader message remains negative: the Eurozone is struggling to create stable, broad-based growth.
The labor market is still holding up better than output. Quarterly employment rose 0.1%, in line with expectations, while annual employment growth stayed at 0.5%. This suggests that the region is not facing a deep employment shock yet. However, weaker output and slower job growth show that the economic cushion is becoming thinner. If activity continues to slow, labor-market resilience may become harder to maintain.
Consumer data also pointed to caution. Eurozone retail sales fell 0.4% month-on-month in April, worse than the expected 0.3% decline and reversing the previous 0.8% rise. On a yearly basis, retail sales increased 1.0%, beating the 0.3% forecast, but slowing from 2.1% previously. This shows that household demand has not collapsed, but the monthly trend is weak. Consumers remain under pressure from inflation, high borrowing costs, and uncertainty around energy prices.
Country-level data were mixed. France showed some resilience, with the trade deficit narrowing to €5.6 billion in April, better than the expected €6.2 billion deficit. Exports rose to €54.6 billion, while the current account also improved. French industrial production increased 0.1% month-on-month, beating expectations for a decline, although momentum slowed from the previous 1.4% rise. Italy, however, showed weaker consumer momentum. Italian retail sales were flat at 0.0%, below the 0.4% forecast, while annual retail growth slowed to 1.6% from 3.8%.
Financial markets reflected this weaker growth backdrop. The euro fell around 0.7% to nearly $1.1525, pressured by soft Eurozone GDP and a stronger U.S. dollar. The dollar strengthened after a strong U.S. jobs report increased expectations that the Federal Reserve may need to raise rates later in 2026. This makes it harder for the euro to recover unless the ECB sounds more hawkish or U.S. inflation data weaken.
Bond markets are another major pressure point. Eurozone government bond yields rose as investors focused on inflation risks linked to elevated energy prices and Middle East tensions. Germany’s 2-year yield rose to 2.654%, while the 10-year yield reached 3.0%. French and Spanish borrowing costs also increased, with France’s 10-year OAT auction yield at 3.80% and Spain’s 10-year Obligacion yield at 3.813%. Higher yields are important because they tighten financial conditions at a time when growth is already weak.
The most important event for the week ahead is the ECB monetary policy meeting on Thursday, June 11. Markets widely expect a 25-basis-point rate hike, likely taking the deposit rate to 2.25%. Because the hike is largely priced in, the bigger market reaction will come from the ECB’s updated forecasts and President Christine Lagarde’s press conference. Investors want to know whether the ECB presents the move as a one-off inflation-control step or signals that another hike remains possible later this year.
The inflation backdrop supports a cautious hawkish stance. Eurozone inflation rose to 3.2% in May, above the ECB’s 2% target, while core inflation increased to 2.5%. Energy remains the biggest external risk because the Middle East conflict and disruption around the Strait of Hormuz continue to keep oil prices elevated. If the ECB upgrades its inflation forecasts, European yields could rise further and pressure rate-sensitive sectors such as real estate, consumer stocks, and high-valuation technology names.
At the same time, the growth picture argues against aggressive tightening. The latest PMIs showed private-sector activity contracting, with the composite PMI falling to 48.5, below the 50 expansion line. Manufacturing remains fragile, new orders are weak, export demand has softened, and input costs are rising. This creates a difficult policy mix: the ECB needs to protect inflation credibility, but it is tightening into a weak economic environment.
European equities face a selective and volatile outlook. Financials may benefit from higher rates, but consumer stocks, real estate, industrial cyclicals, and technology may remain under pressure if yields keep rising. Semiconductor and AI-linked European stocks, including names such as ASML and STMicroelectronics, are also exposed to global profit-taking after the recent selloff in U.S. and Asian chip shares.
The euro remains vulnerable below $1.1600. A hawkish ECB could support a short-term rebound, but strong U.S. CPI or PPI data could keep the dollar dominant and limit euro upside. If EUR/USD fails to reclaim the $1.1550–$1.1600 area, downside pressure may continue.
Overall, the Eurozone enters Week 24 with weak growth, sticky inflation risk, and rising policy tension. The ECB is likely to tighten, but not from a position of strength. The key question is whether policymakers can control inflation expectations without deepening the slowdown. For investors, the best approach remains selective: focus on balance-sheet strength, pricing power, defensive sectors, and companies less exposed to rate-sensitive demand.
EURUSD technical analysis
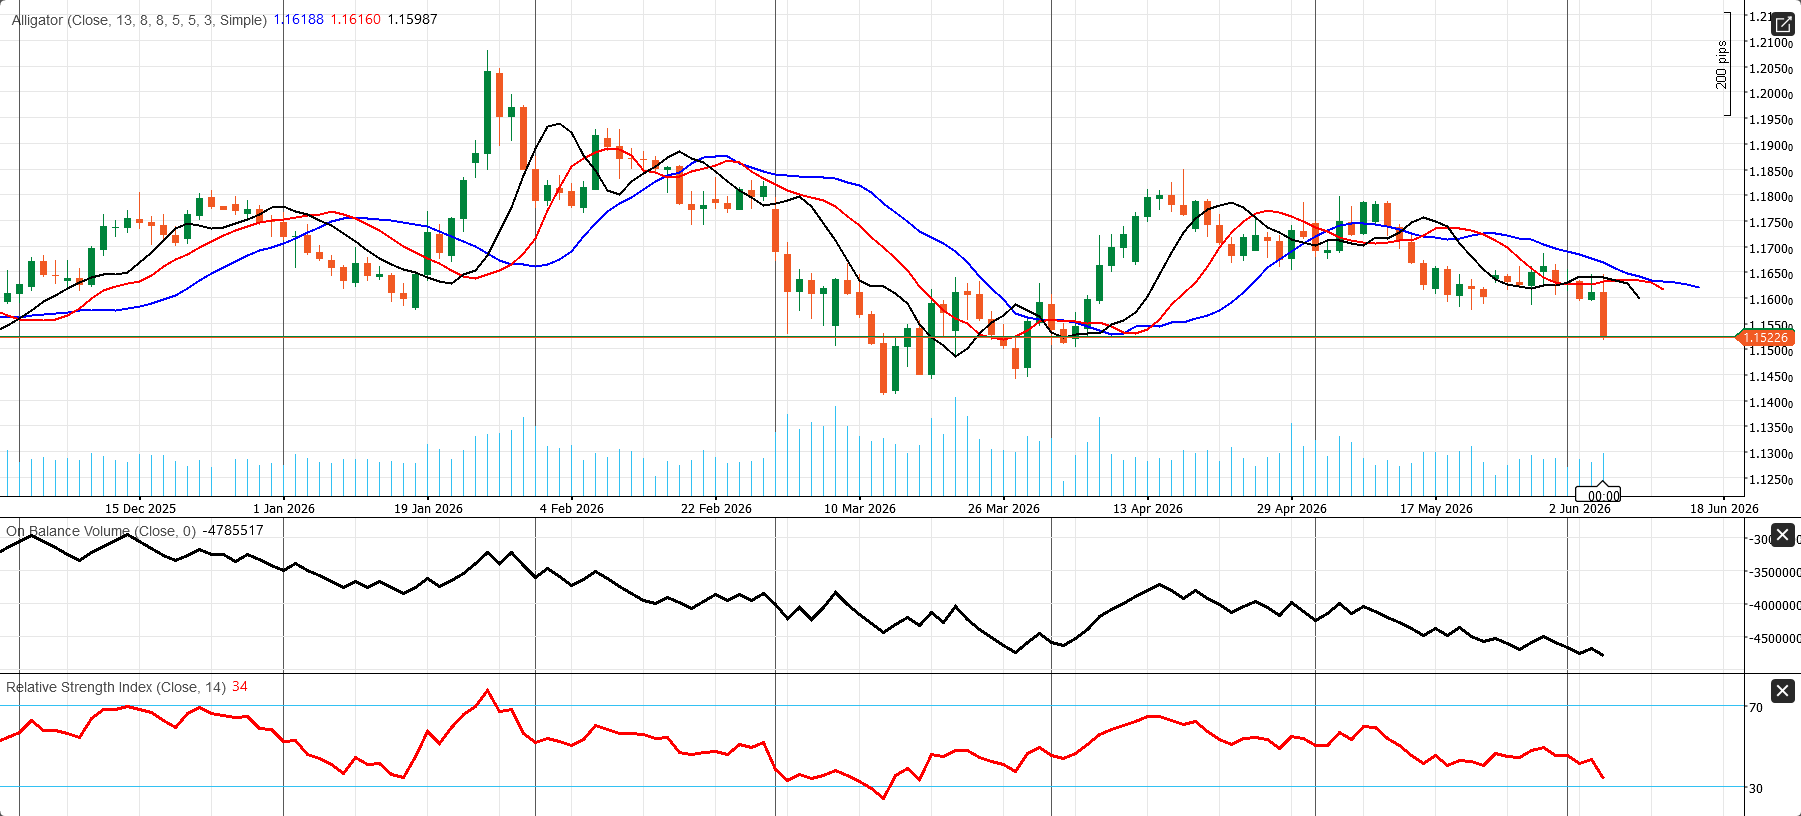
The daily EUR/USD chart has turned clearly weaker. Price is trading around 1.15226, well below the full Alligator cluster, with the slower lines grouped near 1.1599–1.1619. That structure tells me the broader daily trend has shifted back in favor of sellers, and the latest downside move is not just noise inside a range.
From a price-action perspective, the pair has now slipped under the important 1.1550 area and is pressing the lower edge of the recent range. As long as EUR/USD stays below 1.1599–1.1619, rallies still look corrective rather than trend-changing. The first support now sits around 1.1500, and a daily break below that area would expose the next downside zone near 1.1450. On the upside, the first recovery barrier is 1.1550, while the more important resistance remains the Alligator cluster near 1.1600–1.1620.
The secondary indicators confirm the softer tone. On-Balance Volume remains deeply negative and still trends lower, which shows that the broader move has not been backed by fresh accumulation. RSI is near 34, which means downside momentum is already stretched, but it is not yet a reversal signal by itself. In practical terms, this is a bearish daily chart with rebound risk, not a bullish setup.
Gold Market Outlook:
Strong U.S. Jobs Data Pushes Gold Into a Rate-Driven Selloff
Gold enters the week of June 8–14, 2026, under heavy pressure after stronger U.S. labor data, rising Treasury yields, and a stronger U.S. dollar broke the recent precious-metals momentum. The market had started the previous week with support from Middle East tensions, uncertainty around U.S.-Iran diplomacy, and restrictions near the Strait of Hormuz. However, by the end of the week, the main driver had clearly shifted from safe-haven demand to Federal Reserve policy risk.
The key trigger was the May U.S. jobs report. Nonfarm payrolls increased by 172,000, far above the 85,000 forecast, while the unemployment rate held steady at 4.3%. Wage growth also stayed firm, with average hourly earnings rising 0.3% month-on-month. This confirmed that the U.S. labor market remains resilient, even with higher oil prices and geopolitical uncertainty. For gold, the problem is that strong labor data reduce the case for rate cuts and increase the risk that the Fed may need to stay restrictive for longer or even raise rates later in 2026.
Treasury yields reacted immediately. The 2-year yield rose to 4.115%, while the 10-year yield climbed to 4.53%. At the same time, the U.S. Dollar Index jumped to 100.06, its highest level since early April. This combination was strongly negative for gold and silver because both metals do not pay yield. When real-yield expectations rise, and the dollar strengthens, the opportunity cost of holding precious metals increases.
Gold sold off sharply on Friday. Spot gold dropped 3.3% to $4,325.96/oz, while gold futures fell 3.4% to $4,352.57/oz. Earlier in the week, spot gold was already heading for a weekly loss of around 2.2%, its worst weekly decline since early May. The Friday selloff confirmed that investors were no longer treating gold mainly as a geopolitical hedge; they were pricing it as a rate-sensitive asset.
Silver also weakened. Spot silver fell to around $72.63/oz and was down about 3.5% for the week. Silver faced the same pressure as gold from a stronger dollar and higher yields, but it also carried extra risk because it has an industrial-demand component. The sharp selloff in technology, semiconductors, and crypto added pressure to silver because investors were reducing exposure to growth-sensitive assets.
The most important lesson from the week is that geopolitical risk alone was not enough to protect precious metals. Middle East tensions remained active, including uncertainty around the Israel-Lebanon ceasefire process, U.S.-Iran talks, and restrictions around the Strait of Hormuz. Normally, these conditions would support gold. But markets treated the conflict mainly as an inflation risk, not a pure safe-haven shock. Higher oil prices increase inflation concerns, which can push the Fed toward tighter policy and hurt gold.
For the week ahead, the most important event will be U.S. CPI on Wednesday, June 10. A hotter-than-expected CPI report would likely extend bearish pressure on gold because it would strengthen expectations that the Fed may keep rates higher for longer. In that case, Treasury yields could rise further, the dollar could remain strong, and gold could test lower support levels.
U.S. PPI on Thursday, June 11, will also be important. Markets want to know whether higher energy, transport, and supply-chain costs are feeding into broader producer inflation. A strong PPI report would likely create another wave of selling in gold. Weekly jobless claims will also matter. If claims remain low, the labor-market resilience story will stay intact, supporting yields and the dollar. If claims rise meaningfully, gold could find some support.
The University of Michigan Consumer Sentiment report on Friday, June 12, will be important mainly because of inflation expectations. If one-year or five-year inflation expectations rise, gold may not benefit immediately because markets may treat that as another Fed-tightening signal. If expectations ease, gold could recover part of its recent decline.
Technically, gold’s short-term picture has weakened. The first major support zone is $4,300–$4,320. A clean break below $4,300 could expose $4,250, then $4,200. If selling accelerates after hot inflation data or weak Treasury auctions, gold could even test the $4,150–$4,180 area. On the upside, the first resistance zone is $4,350–$4,370. Gold needs to reclaim this area to reduce immediate bearish pressure. A stronger recovery would require a move above $4,400, while $4,450–$4,470 is the larger resistance area.
The base case for Week 24 is a neutral-to-bearish gold outlook. Gold may continue to sell into rallies unless CPI or PPI are soft enough to pull Treasury yields lower. A bullish scenario would require softer inflation data, strong Treasury auction demand, DXY falling below 99.50, and geopolitical risk staying elevated. In that case, XAUUSD could rebound toward $4,400–$4,450. A bearish scenario would develop if CPI or PPI are hot, DXY holds above 100, and markets price a stronger chance of a Fed hike. In that case, gold could break below $4,300 and move toward $4,250–$4,200.
Overall, gold enters Week 24 in a fragile position. The long-term safe-haven argument remains valid, but the short-term market is dominated by the stronger dollar, higher yields, and Fed tightening risk. Unless U.S. inflation data surprise to the downside, gold may struggle to rebuild bullish momentum.
Energy Market Outlook:
Oil Remains Supported as Middle East Risk Keeps Supply Premium Alive
The energy market enters the week of June 8–14, 2026 with a bullish but volatile structure. Crude prices pulled back on Friday after operations at a key port in Oman returned to normal, but the broader weekly trend remained supportive. Both major oil benchmarks snapped a two-week losing streak, supported by Middle East tensions, restricted energy flows through the Persian Gulf, tight refined product inventories, and strong U.S. crude exports.
Brent crude futures for August delivery fell 2.3% on Friday to settle at $92.89 per barrel, while WTI crude futures for July delivery dropped 3.0% to $90.25 per barrel. Despite the Friday decline, Brent gained 0.9% for the week, while WTI rose 3.2%. This shows that the market is not moving in a straight bullish line, but dips are still being supported by geopolitical risk and tightening physical balances.
The main driver remains the Middle East conflict. Hezbollah rejected the U.S.-brokered Israel-Lebanon ceasefire framework, reducing hopes for a quick diplomatic breakthrough between the U.S. and Iran. Iran has made an end to fighting in Lebanon a key condition for progress with Washington, so the failure of the ceasefire process keeps the broader peace track uncertain. At the same time, the Strait of Hormuz remains effectively restricted, putting global energy flows through the Persian Gulf under severe pressure.
This means oil continues to carry a strong geopolitical risk premium. Any credible headline about progress in U.S.-Iran talks, a durable Israel-Lebanon ceasefire, or a clear reopening path for Hormuz could push crude lower quickly. However, any renewed strikes, tanker disruption, or escalation around Kuwait, Bahrain, Oman, Qeshm Island, or southern Lebanon could trigger another sharp rally. In this environment, traders are likely to react strongly to headlines.
The physical market also remains tight. U.S. crude inventories fell by around 8 million barrels in the week ended May 29, much larger than expectations for a 3 million-barrel draw. U.S. crude exports rose to 5.9 million barrels per day, one of the highest levels on record, as buyers in Europe and Asia searched for alternative supplies amid Middle East disruptions. This shows that oil strength is not only based on fear; it is also supported by real supply stress.
Refined product markets are even tighter. Diesel, gasoline, and residual fuel inventories remain at or near the bottom of historical ranges, keeping refinery margins elevated. This is important because tight product inventories can support crude prices even when headline oil prices face short-term profit-taking. If gasoline and distillate inventories continue to draw down during the summer demand season, the oil market could remain well supported.
China is another key factor. China’s crude imports fell by roughly 4.3 million barrels per day between February and May, while the IEA emergency reserve release has been running at an estimated 3.3 million barrels per day across April and May. If emergency releases end by late July, physical markets could tighten further. This creates a risk that current supply relief may prove temporary, especially if Hormuz restrictions remain in place.
On the U.S. supply side, drilling activity has increased only slightly. The Baker Hughes oil rig count rose to 431 from 429, while the total rig count increased to 563 from 562. These small increases suggest marginally stronger drilling activity, but not enough to change the short-term supply picture. For now, geopolitical risk, inventory draws, and product tightness remain more important than U.S. rig growth.
The macro impact of oil is also critical. Elevated crude prices are feeding inflation concerns at a time when the U.S. labor market remains strong. This has contributed to higher Treasury yields, a stronger U.S. dollar, weaker gold, and pressure on high-duration equities. A Boston Fed study suggested that the U.S. economy is less vulnerable to oil shocks than it was in the 1970s, but a 33% oil-price shock could still add 1.5 percentage points to PCE inflation over the following year. That reduces the risk of a classic stagflation shock, but it does not remove the inflation problem.
For the week ahead, the first major event will be the EIA Short-Term Energy Outlook on Tuesday, June 9. Traders will focus on U.S. production forecasts, global supply losses, demand destruction, refinery activity, and price assumptions. If the EIA signals that Hormuz disruptions and inventory draws may last longer, oil could receive fresh support. If the report shows stronger non-OPEC supply or weaker demand, upside may be limited.
The second key event will be the EIA Weekly Petroleum Status Report on Wednesday, June 10. Markets will watch crude inventories, Cushing stocks, gasoline inventories, distillate inventories, refinery utilization, and U.S. exports. Another large crude or product draw would be bullish. A surprise inventory build could trigger profit-taking, especially after last week’s gains.
U.S. inflation data will also matter. CPI is due on Wednesday, and PPI follows on Thursday, June 11. Strong inflation data could lift the dollar and Treasury yields, which may pressure commodities. However, if inflation is mainly driven by energy costs, crude could remain supported by the supply-risk story.
Technically, Brent’s key support zone is $90–$91. As long as Brent holds above this area, the broader structure remains constructive. A break below $90 could open downside toward $88, especially if diplomacy improves or inventories build. On the upside, resistance sits around $95–$96, then $98–$100. For WTI, the key support zone is $88–$90. A break below $88 could trigger deeper profit-taking toward $85–$86, while resistance sits near $93–$94, then $96–$98.
The base case for Week 24 is neutral-to-bullish. Brent is likely to trade mostly in the $90–$98 range, while WTI may move around $88–$96. Dips remain buyable while Hormuz restrictions, inventory draws, and Middle East uncertainty remain active. The bullish scenario would require renewed escalation, stalled U.S.-Iran talks, restricted tanker traffic, and another major EIA inventory draw. In that case, Brent could retest $98–$100, while WTI could move toward $96–$98.
The bearish scenario depends on diplomatic relief. If U.S.-Iran talks improve, the Lebanon ceasefire process revives, Oman port normalization reduces disruption fears, and EIA inventories build, Brent could fall below $90 and test $88, while WTI could break below $88 and move toward $85–$86.
Overall, the energy market starts Week 24 with a clear supply-risk premium. Oil is no longer trading only on demand expectations; it is being priced as a geopolitical, inflation, and supply-security asset. Until there is credible progress toward reopening energy flows through the Persian Gulf, crude is likely to remain supported on dips.
Crypto Market Outlook:
Bitcoin Defends $60,000 as ETF Outflows and Fed Risk Pressure Sentiment
The crypto market enters the week of June 8–14, 2026 in a defensive position after one of its weakest weekly performances in months. Bitcoin briefly broke the key $ 60,000 level below, fell to its lowest level since October 2024, and headed for a weekly loss of more than 16%. The selloff was not driven by one single factor. It came from a combination of heavy ETF outflows, stronger U.S. rate-hike expectations, a firmer U.S. dollar, Strategy’s rare Bitcoin sale, geopolitical uncertainty, and capital rotation away from crypto toward AI-linked equities.
Bitcoin was last down 2.4% on Friday at $61,749.7, after touching an intraday low of $59,159.3. The break below $60,000 was important because it was both a psychological and technical warning. It confirmed that short-term sentiment had turned sharply negative and that buyers were no longer defending key levels with the same confidence seen earlier in the cycle.
The biggest pressure point remains spot Bitcoin ETF flows. Bitcoin ETFs recorded around $1.4 billion in outflows during the week, marking the fourth consecutive week of more than $1 billion in withdrawals. This is a major negative signal because ETF flows have become one of the clearest real-time measures of institutional demand. The latest data suggest that large investors are not only taking profit but actively reducing exposure. Until ETF outflows slow, Bitcoin rallies may remain vulnerable to renewed selling.
Strategy’s Bitcoin sale also damaged market confidence. The company sold part of its Bitcoin holdings for the first time since late 2022. Although the sale was small, its psychological impact was significant because Strategy has long been seen as the leading corporate Bitcoin treasury vehicle. The move raised new questions about whether corporate Bitcoin treasury models remain sustainable when Bitcoin does not generate yield or cash flow, and companies may eventually need liquidity.
The macro backdrop is also unfavorable. The stronger-than-expected U.S. jobs report increased expectations that the Federal Reserve may need to raise interest rates later in 2026. Higher rate expectations pushed Treasury yields upward and strengthened the U.S. dollar. For crypto, this is a difficult environment because Bitcoin and altcoins are non-yielding risk assets. When Treasury yields rise, investors have less incentive to hold speculative assets that do not produce income.
Geopolitical risk added another layer of pressure. The U.S.-Iran conflict, renewed Middle East tensions, and uncertainty around the Strait of Hormuz increased risk aversion across global markets. Crypto did not behave like a safe haven. Instead, it traded like a high-beta risk asset, falling alongside technology stocks, growth names, and other speculative markets. Investors moved toward the dollar rather than digital assets.
Capital rotation also hurt crypto. Investors increasingly favored AI-linked equities and next-generation technology themes over digital assets. Market attention shifted toward companies and themes linked to SpaceX, OpenAI, Anthropic, Quantinuum, Nvidia, and broader AI infrastructure. For many investors, AI equities currently offer stronger earnings visibility, clearer business models, and a more powerful growth narrative than non-yielding crypto assets.
Altcoins performed even worse than Bitcoin. Ethereum fell 8.3% on Friday to $1,615.74, hit a 14-month low, and lost around 20% for the week. XRP dropped to $1.1144 and fell more than 15% for the week. Solana declined 3.8%, Cardano dropped 10.1%, and BNB lost 3.6%. Dogecoin fell 4.6%, while $TRUMP dropped 8.6%. The broad weakness confirmed that the selloff was not isolated to Bitcoin. It became a full crypto-market deleveraging move.
Crypto-related equities also weakened. Coinbase, Strategy, and mining stocks came under pressure as Bitcoin declined. This shows that investors were cutting exposure across the entire crypto ecosystem, including tokens, exchanges, corporate Bitcoin holders, and miners. Weakness in crypto equities often reinforces negative sentiment in the underlying assets.
Retail and U.S. demand also looked soft. The Bitcoin Coinbase Premium Index showed Bitcoin trading at a deep discount on Coinbase compared with the global average. A negative Coinbase premium is important because it suggests that U.S. retail and institutional demand are not yet strong enough to absorb supply or lead a recovery. Without stronger U.S. demand, Bitcoin may struggle to build a sustainable rebound.
The technical picture has weakened materially. Bitcoin’s most important support zone is now $59,000–$60,000. A confirmed daily or weekly close below this area could open the way toward $56,000–$57,000, followed by bigger risk toward $52,000–$54,000 if ETF outflows accelerate. On the upside, Bitcoin must reclaim $63,500–$65,000 to show that sellers are losing control. A move above $65,000 could improve short-term sentiment and open a recovery toward $68,000–$70,000.
For Week 24, the key macro events are U.S. CPI on Wednesday, June 10, U.S. PPI on Thursday, June 11, weekly jobless claims, and the University of Michigan consumer sentiment and inflation expectations report on Friday, June 12. A hot CPI or PPI report would likely support the dollar, push yields higher, and increase pressure on Bitcoin. A softer inflation report could give BTC room for a relief rebound by reducing rate-hike fears.
The base case is a bearish-to-neutral crypto outlook. Bitcoin may trade mostly in the $59,000–$65,000 range, with oversold conditions creating short-term rebounds but ETF outflows and macro pressure limiting upside. A bullish scenario would require softer inflation data, slower ETF redemptions, an improved Coinbase premium, and a break back above $65,000. A bearish scenario would develop if inflation is hot, DXY stays above 100, yields rise further, and ETF outflows continue above $1 billion weekly.
Overall, the crypto market remains fragile. The long-term digital-asset story has not disappeared, but short-term conditions are clearly negative. Until institutional flows stabilize, U.S. demand improves, and Bitcoin reclaims $65,000, the market bias remains defensive, with Bitcoin and major altcoins still vulnerable to further downside.
FAQ
1. Why are global markets under pressure in Week 24 of 2026?
Global markets are under pressure because investors are dealing with a difficult mix of strong U.S. labor data, higher Treasury yields, stronger dollar demand, oil-price risks, inflation concerns, geopolitical uncertainty, and heavy profit-taking in technology stocks.
2. Why is the U.S. CPI report important for global markets this week?
The U.S. CPI report on Wednesday, June 10, is important because it will show whether inflation is cooling or staying sticky. A hotter CPI reading could support a more hawkish Federal Reserve outlook, push Treasury yields and the U.S. dollar higher, and pressure equities, gold, crypto and emerging-market currencies.
3. How did the latest U.S. jobs report affect Federal Reserve expectations?
The stronger-than-expected U.S. jobs report increased expectations that the Federal Reserve may keep interest rates restrictive for longer or even consider further tightening later in 2026. This hawkish repricing pushed Treasury yields and the U.S. dollar higher.
4. Why did technology stocks sell off sharply?
Technology stocks sold off because valuations had become stretched after the AI-led rally. When Treasury yields rose after the strong U.S. jobs report, high-duration growth stocks, semiconductor names and AI-related trades became more vulnerable to profit-taking.
5. How are oil prices affecting inflation fears?
Oil prices remain a major inflation risk because Brent and WTI are trading near or above the $90 level. Higher energy costs can feed into transport, production and consumer prices, making it harder for central banks to ease policy.
6. What could support gold prices in Week 24?
Gold could recover if U.S. CPI or PPI data come in softer than expected, Treasury yields fall, the U.S. dollar weakens, or geopolitical risks increase safe-haven demand. However, as long as yields and the dollar remain firm, gold may stay under pressure.
7. Why is Bitcoin weak in the current market environment?
Bitcoin is weak because risk appetite has deteriorated, rate expectations have moved higher, spot Bitcoin ETFs have seen heavy outflows, and capital has rotated away from speculative assets. A recovery may require Bitcoin to reclaim the $63,500–$65,000 area.
8. What is the key risk for emerging markets this week?
The main risk for emerging markets is the combination of higher U.S. Treasury yields, a stronger dollar, oil volatility, and weaker global risk appetite. These conditions can pressure EM currencies, equities, and external financing conditions.
9. Why is the ECB meeting important for European markets?
The ECB meeting on June 11 is important because markets expect a 25-basis-point rate hike, but investors will focus more on whether policymakers signal additional tightening. A hawkish ECB could support the euro but may also pressure European equities given weak growth momentum.
10. What is the base-case market outlook for Week 24?
The base case is elevated volatility and selective risk-taking. Softer U.S. inflation data could trigger a relief rally, weaken the dollar, and support equities, gold, and crypto. Hot inflation, higher oil prices, weak Treasury auction demand, or continued semiconductor selling would likely keep markets defensive.
Comments