 English
 پارسی


Executive summary
Risk tone is mixed-to-defensive into the European morning: Asia equities are uneven but broadly resilient (Japan and Hong Kong higher), while the latest U.S. close shows continued tech-led softness. NVIDIA sentiment remains central to the “AI valuation” debate, nudging investors toward selective de-risking and safe-haven positioning.
FX is largely range-bound, with modest USD weakness versus AUD/NZD but firmness versus TRY and CNH. China leaned against further yuan gains via a forward-market policy tweak, reinforcing a “managed appreciation” signal.
Commodities are bid in precious metals and oil, consistent with lower U.S. yields + geopolitical risk premium; natural gas is slightly lower. Crypto is softer (BTC/ETH down), tracking a cautious risk backdrop.
Drivers and cross-asset read-through
Geopolitics is the near-term volatility catalyst:
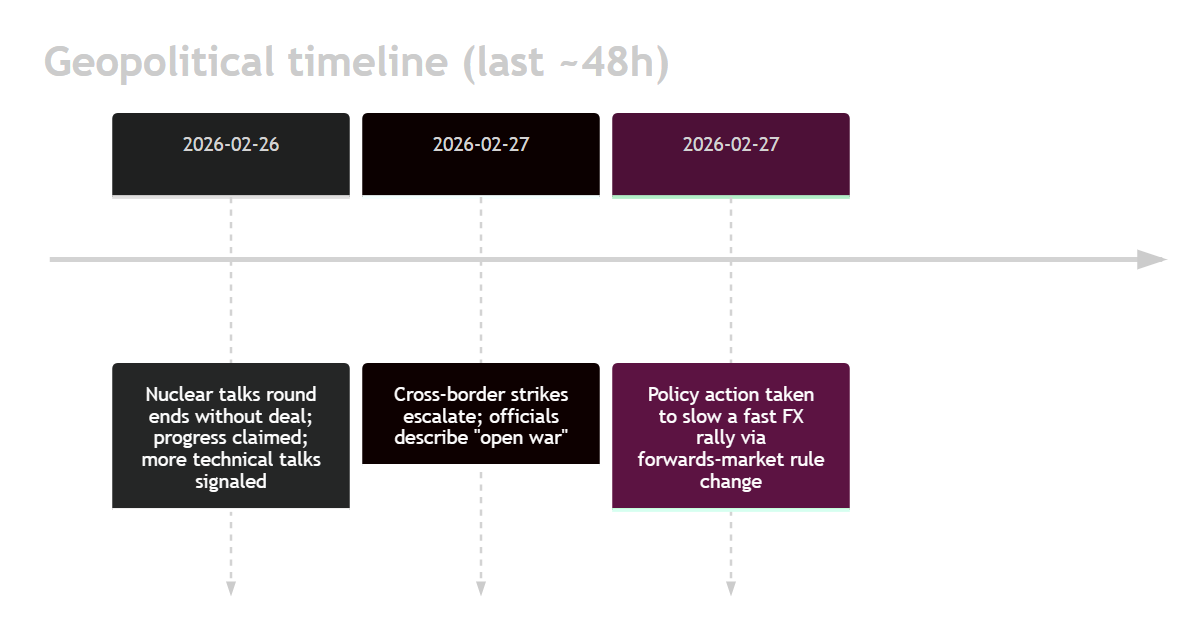
- Tensions between the Islamic Republic of Iran and the United States of America continue, but now the war scenario has become stronger, especially after yesterday's talks in Geneva, which did not yield any tangible results.
- Pakistan escalated strikes into Afghanistan, and officials used “open war” language, reinforcing classic “risk-off” hedges (JPY strength tendencies, gold bid) and supporting crude’s risk premium.
In FX, People's Bank of China actions to temper a yuan rally (via forwards-market rule changes) helped cap CNH gains and signaled policy unease with one-way moves.
Rates narrative remains pivotal: falling yields have lowered the opportunity cost of holding gold, contributing to bullion resilience even as headline “safe-haven” demand fluctuates with each geopolitical headline.
Macro data and releases
Japan: Ministry of Economy, Trade and Industry reported January industrial production up +2.2% m/m (seasonally adjusted) and +2.3% y/y (original); the production forecast points to a -0.5% m/m February decline (survey) and -2.6% m/m in March.
Inflation signal: Tokyo CPI data showed a moderate dynamic (still above/near target on core measures), which keeps policy expectations sensitive for Bank of Japan watchers.
North America (upcoming): the Bureau of Labor Statistics schedules January PPI for 08:30 ET (noting prior delay risk), while Statistics Canada is set to publish official Q4 and full-year GDP (income/expenditure) today.
Geopolitics and policy
United States–Iran nuclear negotiations ended without a deal but with both sides/mediators highlighting progress; any path toward sanctions relief would be a medium-term bearish supply shock for oil, while breakdown risk keeps the near-term risk premium intact.
Oman played a key mediation role; markets are also tracking second-round effects via energy, EM FX, and safe-haven demand.
Trading implications and risks
Near-term positioning leans toward “defensive carry + event hedges”: JPY strength and gold resilience can persist if geopolitical headlines intensify or if tech-led equity weakness deepens. CNH risk remains asymmetric—policy leaning against rapid appreciation raises the bar for sustained USD/CNH downside.
Key 24–48h risk is data-driven: U.S. PPI and Canadian GDP are the next high-beta releases for rates, USD, and equity duration; any upside inflation surprise would likely re-steepen “higher-for-longer” pricing and pressure risk assets again.
Comments